

By Penny Laneford | January 15, 2026
Copper hit a record $13,310 per metric ton on the London Metal Exchange in early January 2026 — a 52% surge from approximately $8,700 per ton at the start of 2025. The rally obliterated previous price ceilings and sent shockwaves through global commodity markets. For miners, traders, and anyone connected to the energy transition, this rally signals a fundamental reshaping of the copper market, driven by an unlikely new force: artificial intelligence.
What Is Driving the 2026 Copper Price Record?
Three forces drive the 2026 copper price surge to record highs: explosive AI data center construction, accelerating renewable energy deployment, and major supply disruptions at key mining operations worldwide. Copper posted roughly a 40% gain through all of 2025, then added another 6% in just the first two weeks of January 2026 — momentum that traditional demand sources alone cannot explain.
Why Is AI Pushing Copper Prices to Record Highs?
Every AI data center devours copper. Server racks, cooling systems, and the miles of cabling connecting these massive facilities to the power grid all require substantial quantities of the metal. As tech giants race to build AI infrastructure at a frantic pace, copper demand from this sector alone has transformed global market dynamics.
Goldman Sachs analysts confirmed that “massive spending on artificial intelligence gave prices an extra boost” throughout 2025 — a trend that accelerated dramatically as 2026 began. The bank’s research identifies AI and data center investment as a primary demand driver for industrial metals across the board.
Tin, a proxy for computing sector activity, also surged 30% since the start of 2026 — a parallel rally that confirms how aggressively the tech sector pulls on metal supplies.
How Does Renewable Energy Add to Copper Demand?
AI does not operate in isolation. The global push toward renewable energy compounds copper demand pressures simultaneously. Solar installations, wind farms, and electric vehicle infrastructure all require significantly more copper than their fossil fuel equivalents.
- A single wind turbine contains up to 4.7 tons of copper
- Electric vehicles use roughly four times more copper than conventional gasoline cars
- Solar panel arrays and grid-scale battery storage systems add further copper intensity to every megawatt of new clean energy capacity
This convergence — AI buildout and the green energy transition happening simultaneously — creates what industry analysts describe as a “demand supercycle” for copper. The implications extend well beyond commodity trading floors: mining operations worldwide face mounting pressure to increase output, even as ore grade quality at existing mines continues to decline and new project timelines stretch into the decade-plus range.
What Supply Problems Are Pushing Copper Prices Higher?
Demand alone does not explain $13,310 copper. Major supply disruptions at key mining operations have tightened global availability at precisely the wrong moment.
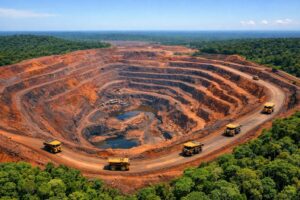
Kamoa-Kakula in the Democratic Republic of Congo and Grasberg in Indonesia — two of the world’s most significant copper producers — both encountered operational challenges that constrained output. South America, traditionally the backbone of global copper supply, faces a perfect storm of problems:
- Extreme weather events disrupted operations across Chile and Peru
- Labor strikes continue to plague multiple facilities
- Political uncertainty in key producing nations adds a risk premium to every ton extracted
Then there is the tariff wildcard. Fears of potential U.S. tariffs on refined copper triggered aggressive stockpiling in American warehouses, redirecting global shipments and tightening supply elsewhere. Traders scrambled to position inventory ahead of any policy changes, creating artificial scarcity in non-U.S. markets — a geopolitical chess match that moves prices regardless of actual supply-demand fundamentals.
What Does Goldman Sachs Forecast for Copper Prices in 2026?
Goldman Sachs Research expects the global copper market to remain in a 160,000-tonne surplus throughout 2026. The bank forecasts prices averaging $10,710 in the first half of the year, with a trading range between $10,000 and $11,000 per ton through most of the period — well below current spot prices.
That gap suggests either Goldman’s models underestimate demand, or the market prices in substantial risk premiums beyond pure supply-demand math. The bank attributes elevated prices to “risk premiums and strategic positioning” rather than physical tightness: traders pay up for copper not because supplies are actually scarce today, but because they fear scarcity is coming.
This distinction matters enormously for miners weighing capital allocation decisions. A rally built on physical shortage justifies aggressive expansion. A rally built on fear-driven positioning can reverse sharply if geopolitical tensions ease or demand growth disappoints.
Will Copper Reach $15,000 Per Ton by 2035?
Goldman Sachs projects copper reaching $15,000 per ton by 2035 — a target that seemed ambitious when analysts first proposed it, but looks increasingly conservative given current price trajectories. Three structural realities support that long-term forecast:
- New mines take 15–20 years to develop from discovery to production — meaning supply cannot respond quickly to demand surges
- Ore grade quality at existing mines keeps declining — operators must move more earth to extract the same volume of copper, driving up energy and operating costs
- Demand from AI, electrification, and renewable energy shows no sign of slowing — if anything, it accelerates year over year
Permitting challenges in developed markets extend project timelines further, adding another structural constraint that no amount of capital spending resolves quickly.
What Does the Copper Price Surge Mean for the Mining Sector?
For copper producers, $13,310 prices translate directly into margin expansion and stronger project economics. Operations that were marginal at $8,000 per ton now generate substantial cash flow. Exploration budgets expand. M&A activity accelerates as majors seek to lock in future supply.
For copper consumers — automakers, construction firms, and tech companies building AI infrastructure — the calculus grows more challenging. Higher input costs ripple through supply chains, alternative materials gain relative attractiveness, and recycling economics improve as secondary copper becomes more valuable.
Strategic implications reach national policy as well. Countries that depend on copper imports face balance of payments pressure. Resource-rich nations gain enhanced geopolitical leverage. Strategic mineral policy increasingly dominates trade discussions at the highest levels of government.
What Is the Outlook for Copper Beyond 2026?
Copper’s record-breaking rally represents more than a commodity price move. It signals a fundamental shift in how the global economy values the materials underlying electrification and digitalization. Whether current prices prove sustainable or overshoot fair value, the structural forces driving copper demand — AI buildout, renewable energy transition, electric vehicle adoption — are not going away.
For an industry accustomed to boom-bust cycles, the current environment presents both unprecedented opportunity and significant execution risk. The miners who navigate this moment successfully will shape the next decade of the energy transition. The ones who fail to act will watch from the sidelines as copper reshapes the world without them.
This report draws from London Metal Exchange trading data and Goldman Sachs analyst reports. Additional reporting on mining sector developments is available at Skillings Mining Review.
You might also be interested in: