By Salini Krishnan
Target publish time: 4:00 PM ET

Mining investors are weighing three connected signals: a widening gap between public-market valuations and transaction prices, continued demand for royalty and streaming capital, and copper’s retreat from a record ahead of the next U.S. tariff decision.
The common theme is selectivity. Strategic buyers are paying for permitted resources, infrastructure and processing access, while investors are testing whether headline asset values can translate into deliverable net asset value (NAV), cash flow and funded construction.
Market snapshot
| Commodity | Reference level | Type | Main investment read-through |
|---|---|---|---|
| Copper | US$14,000–14,055/t | LME reference | Three-week low after retreat from the record near US$14,854/t; Sept. 30 Section 232 decision remains the key catalyst |
| Gold | About US$4,270/oz | Spot reference | Higher rate-hike expectations and a 10-year Treasury yield above 5% are near-term headwinds; Goldman Sachs retains a roughly US$4,900 year-end view |
| Silver | About US$63/oz | Spot reference | Sixth consecutive annual deficit supports the long-term case, but volatility remains elevated |
| Lithium carbonate | RMB140,000–185,000/t | Working scenario range | Inventory reporting changes have pressured prices; Jianxiawo and fourth-quarter battery demand are key variables |
| Nickel | US$17,000–19,000/t | Scenario range | Indonesian RKAB ore quotas remain the principal supply swing factor |
| Uranium | About US$90/lb | Spot reference | Term-market activity is strengthening as utilities return to contracting |
Valuation gap: royalty platforms still command the premium
Royalty and streaming platforms continue to trade at a substantial premium to operating miners. The current reference ranges place royalty and streaming companies at approximately 1.2x–2.0x P/NAV, compared with 1.1x–1.2x for copper majors.
Mid-tier copper companies generally trade around 0.5x–0.8x P/NAV, while gold juniors and developers sit near 0.4x–0.6x. Early-stage explorers are typically valued at roughly 0.3x–0.45x P/NAV.
Recent M&A has been clearing at approximately 0.73x deliverable NAV. That measure is more useful than headline resource value because it accounts for the portion of a project that can realistically be funded, permitted, built and brought into production.

A low P/NAV is therefore an investigation trigger, not proof of undervaluation. The discount may reflect permitting delays, weak metallurgy, infrastructure constraints, high capex, jurisdictional risk or insufficient balance-sheet runway.
Royalty platforms receive higher multiples because they participate in mine revenue without directly carrying most labour, energy, sustaining-capital and construction costs. The premium remains justified only when the underlying operators can deliver production and the royalty portfolio is sufficiently diversified.

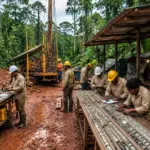
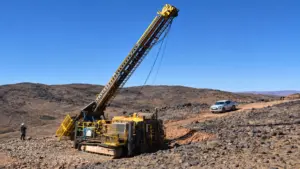
Drill core verification remains an early test of whether a resource can support a higher valuation.
M&A intelligence: strategic access is driving deal structures
Recent transactions show buyers targeting supply-chain control as well as mineral resources.
-
Atlantic Lithium is advancing a proposed US$210 million all-cash takeover by Zhejiang Huayou Cobalt. The transaction is subject to shareholder, court and regulatory approvals in Australia, Ghana and China. The scheme booklet is expected in October, with a shareholder vote planned for November and implementation targeted for December. The principal asset is the Ewoyaa lithium project in Ghana. Background on the transaction.
-
Generation Mining has completed C$340 million of final funding, closing a roughly C$1.3 billion construction package for the Marathon copper-palladium project in Ontario. The package includes a C$200 million bought deal, a C$40 million Canada Growth Fund private placement and C$100 million of convertible notes. Early works construction is expected in the fourth quarter. The financing reduces project-level funding uncertainty but also introduces material dilution and conversion risk.
-
Lithium Argentina closed a US$180 million strategic investment from Ganfeng Lithium through a six-year, 4.0% unsecured convertible note. The proceeds are intended to help repay US$259 million of convertible debt due in January 2027. At a conversion price of US$12.50 per share, Ganfeng’s ownership could reach approximately 16.1% on a fully diluted basis. Company announcement.
-
Solar Industries India has made an approximately R21.8 billion, or US$1.4 billion, all-cash offer for Omnia Holdings. The transaction would take the South African industrial explosives, fertilizers and chemicals group private, subject to shareholder and regulatory approvals. Transaction coverage.
-
EQ Resources has taken a 10% stake in the Springer tungsten complex joint venture with The Elmet Group and Blue Moon Metals. The broader transaction involves reported restart funding of approximately US$150 million–US$175 million for the Nevada processing complex and includes long-term tungsten offtake arrangements. Project announcement.
-
Hancock Prospecting is acquiring a 13.5% stake in White Cliff Minerals, adding another example of strategic investors taking positions in earlier-stage critical-minerals exposure.
These transactions vary widely in maturity and financing structure. Their common feature is that buyers are paying for access to scarce jurisdictions, processing routes, infrastructure, offtake and future supply: not simply tonnes in the ground.
Royalty and streaming activity
Royalty deal flow remains active across gold, silver, copper and critical minerals.
Elemental Royalty completed its acquisition of Vizsla Royalties for approximately C$327 million, comprising up to C$82 million in cash and roughly 8.1 million Elemental shares. Vizsla holders received approximately 11.19% of Elemental following completion. The transaction secures 2.0%–3.5% life-of-mine NSRs over the Panuco silver-gold project in Mexico. Elemental transaction details.
Franco-Nevada agreed to pay A$170 million to increase its Bullabulling gold royalty interest to approximately 3.90%, alongside a A$30 million equity subscription in Minerals 260. The A$200 million package expands Franco-Nevada’s exposure to a large Western Australian gold project while giving the developer additional project funding. Minerals 260 financing background.
Vox Royalty completed an A$8.4 million acquisition of the White Dam, Kalman and Sylvania Australian gold and copper royalties. The deal adds producing, development and exploration-stage interests across three jurisdictions in Australia.
Mako Mining signed a non-binding letter of intent with Sailfish Royalty for a 20-year gold purchase agreement. The proposed structure could provide project capital while giving Sailfish long-dated exposure to gold production. Because the agreement remains non-binding, final terms, funding conditions and completion risk remain important.

Royalty structures can transfer project capital without transferring direct operating control.
Commodity outlook: policy premiums meet physical markets
Copper scenario framework
| Scenario | Indicative price range | Main assumptions |
|---|---|---|
| Bear | US$11,000–13,500/t | Tariff delay, U.S. stockpile release, softer Chinese demand and stronger scrap flows |
| Base | US$12,800–14,500/t | Physical tightness persists while the policy premium moderates |
| Bull | US$15,000–16,000/t | Tariffs are implemented and ex-U.S. inventories tighten |
Copper has fallen from the September record near US$14,854/t to around US$14,000–14,055/t, with new LME deliveries suggesting some supply relief. The COMEX-LME spread has narrowed, reducing part of the incentive to move additional metal into the United States.
The Sept. 30 Section 232 decision window remains the central catalyst. Citi continues to hold a bullish three-month target near US$15,000/t, but the upside depends on tariffs being implemented and non-U.S. inventories tightening.
The key analytical distinction is between stockpiling and genuine consumption. Investors should monitor warehouse withdrawals, regional premiums, scrap flows, Chinese imports and cash-to-three-month spreads. If U.S. stocks remain unavailable to the international market, the bull case strengthens. If metal returns to the seaborne market after a tariff delay, the policy premium could unwind.
Gold near US$4,270/oz has eased as stronger rate-hike expectations and a 10-year Treasury yield above 5% increase the opportunity cost of holding bullion. J.P. Morgan continues to prioritize gold and copper in its 2026 sector preferences, while Goldman Sachs retains a year-end gold view near US$4,900/oz.
Silver near US$63/oz continues to benefit from a sixth consecutive annual deficit. A working base case of US$65–80/oz reflects structural support but also elevated volatility.
Lithium carbonate prices have weakened after a change in inventory methodology lifted reported Chinese inventories to approximately 175,000 tonnes. Macquarie has characterized the move as information-driven rather than evidence of a fundamental supply-demand shift. The working range is RMB140,000–185,000/t, with the Jianxiawo restart and fourth-quarter battery demand as key variables.
Nickel remains within a US$17,000–19,000/t scenario range, with Indonesian RKAB ore quotas setting the market’s supply floor. Uranium near US$90/lb is supported by stronger term-market activity as utilities become more active in contracting.
For additional context, see Skillings’ copper tariff analysis, lithium supply outlook and gold and silver market coverage.
Investor checklist
- Test NAV using normalized, below-spot commodity prices.
- Separate stockpiling from genuine consumption in copper.
- Review capex, dilution and balance-sheet runway.
- Confirm permitting, court, regulatory and community approvals.
- Assess power, water, transport and processing access.
- Examine royalty burdens and offtake restrictions.
- Compare transaction value with deliverable NAV, not headline resource value.
- Check whether a royalty or stream covers future discoveries, expansions and mine-plan changes.
- Distinguish binding transactions from non-binding letters of intent.
Social snippets
LinkedIn:
Mining valuations are separating between scalable royalty platforms, funded construction projects and earlier-stage assets still carrying execution risk. Our latest Skillings Mining Intelligence digest reviews the P/NAV framework, major M&A closes, royalty transactions and the copper tariff test. Read the full analysis: [link]
X:
Copper is near US$14,000/t after retreating from its record, but the Sept. 30 Section 232 decision remains the key catalyst. We also review royalty premiums, recent mining M&A and base/bull/bear commodity scenarios. Full analysis: [link]
This article is for market information and analysis only. It does not constitute financial advice or a recommendation to buy or sell any security, commodity or financial instrument.
Lithium Power Map
The 2026 Lithium Power Map is available during the presale window for US$59, with regular pricing listed at US$149. Learn more about the Lithium Power Map.