Author: Salini Krishnan

Luca Mining’s agreement to acquire Capstone Copper’s Cozamin mine for up to US$385 million puts a fresh valuation marker on producing, permitted and infrastructure-backed copper assets.
The transaction includes US$290 million upfront, US$275 million in cash and US$15 million in Luca shares, plus up to US$95 million in deferred and copper-price-linked consideration. For investors, the important question is not simply whether the headline price is attractive. It is whether the asset’s deliverable net asset value supports the purchase price under conservative commodity assumptions.
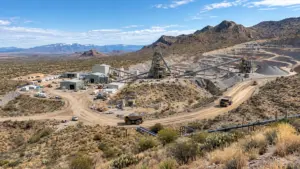
Cozamin has produced continuously underground for about two decades in Zacatecas, Mexico. Its historical mine plan extends to 2030, while Proven & Probable reserves stand at 6.7 million tonnes grading 1.40% copper and 42.2 grams per tonne silver. Luca expects the acquisition to more than double its 2027 production, increase net revenue to approximately US$598 million from US$177 million in 2025 and lift operating cash flow to roughly US$223 million from US$37 million.
That is the valuation reset: buyers are paying for near-term cash generation, operating infrastructure and permits, not simply resource tonnes.
M&A intelligence: Luca buys cash flow, not optionality
Luca’s financing package totals approximately US$300 million:

- US$110 million bought deal, supported by a US$75 million Trafigura equity backstop
- US$40 million concurrent placement with Wheaton Precious Metals and Taurus Mining Finance
- US$125 million senior secured facility from Taurus and Macquarie
- US$25 million capped silver stream from Wheaton, covering an incremental 15% of refined silver up to 500,000 ounces
The deal is targeted to close in the fourth quarter, subject to customary approvals.
Luca’s projected 2027 operating cash flow per share is expected to rise 93% to approximately US$0.42. The structure also limits some commodity risk. Up to US$60 million of the deferred consideration is tied to average annual LME copper prices between 2027 and 2029, while another US$35 million is payable on the first anniversary of closing.
That arrangement allows Capstone to retain exposure to copper-price upside while Luca avoids paying the full maximum value at closing. It also provides a useful framework for analysts: the upfront price can be assessed against base-case NAV, while the contingent payments can be tested against higher copper-price scenarios.
The asset’s value rests on more than grade. Cozamin has established underground workings, processing infrastructure, permits, operating history and a defined reserve base. Those characteristics reduce the development and execution risk that typically drives junior mining discounts.

M&A intelligence: Artemis chooses permitted ounces
Artemis Gold’s agreement to acquire Vista Gold values the company at approximately US$427 million in an all-scrip plan of arrangement. Vista shareholders will receive 0.0966 Artemis shares per Vista share, implying approximately US$2.83 per Vista share and a 29% premium to the 20-day VWAP referenced in the transaction materials.
The strategic asset is Vista’s Mt Todd gold project in Australia’s Northern Territory. Mt Todd contains approximately 9.1 million ounces of Measured and Indicated resources and 1.4 million ounces of Inferred resources, with key permits granted for a 50,000-tonne-per-day processing facility.
Artemis will continue to prioritize Blackwater Phase 1A and the EP2 expansion. Construction spending at Mt Todd is not required before EP2 is completed, allowing the company to acquire a large permitted project without immediately competing for construction capital.
The combination creates a pathway to more than 1 million ounces of annual gold production. Closing is expected in January, subject to Foreign Investment Review Board and Northern Territory ministerial consent.
The transaction illustrates a different form of capital allocation from Luca’s Cozamin purchase. Artemis is using equity rather than debt or a large cash commitment to acquire de-risked ounces. The trade-off is dilution, but the structure protects liquidity while preserving the option to develop Mt Todd after the company’s existing growth program reaches a later stage.
For investors, the relevant comparison is between the implied acquisition value and the cost, timing and risk of building an equivalent permitted project from scratch.
Royalty and streaming deal flow: contract terms matter
Royalty and streaming transactions continue to attract capital because they offer exposure to mine production without direct responsibility for most labour, energy or sustaining-capital inflation.
Empress Royalty’s US$62 million Tongon gold stream in Côte d’Ivoire provides an example of why headline consideration is only the starting point. The stream covers:
- 3.58% of payable gold until 400,000 cumulative ounces are delivered
- 2.93% until cumulative deliveries reach 600,000 ounces
- 0.81% for the remainder of an approximately 29-year term
- Ongoing payments equal to 0.5% of the gold market price for delivered ounces
Empress is funding the transaction with a US$75 million senior secured facility, initially drawing US$55 million.
The broader market includes Elemental Royalty’s approximately C$327 million acquisition of Vizsla Royalties, providing exposure to 2.0%–3.5% life-of-mine NSRs over the Panuco project in Mexico. Franco-Nevada has increased its Bullabulling gold royalty by approximately A$170 million alongside an A$30 million equity subscription in Minerals 260, while Vox Royalty has added an Australian gold and copper royalty package for about A$8.4 million.
Investors should verify six items before comparing these transactions:
- Step-downs, caps and buyback rights
- Counterparty strength and operator liquidity
- Production timing and mine-plan assumptions
- Contract enforceability across jurisdictions
- Remaining capital requirements and metallurgy
- Whether attributable ounces are exposed to one mine or diversified across a portfolio
Summit Royalties expects its producing portfolio to reach six assets, with attributable gold-equivalent ounces more than doubling. That type of portfolio expansion can support a valuation premium, but only if production is delivered on schedule and the underlying operators remain financially capable.

The P/NAV scorecard
Royalty and streaming platforms command a premium because their revenue is less exposed to operating-cost inflation and they generally do not fund mine construction or sustaining capital. They also retain exploration exposure when operators expand resources.
That premium is not transferable automatically to every royalty company. A low P/NAV may indicate overlooked value, but it may also reflect delayed production, weak counterparties, contract uncertainty or an overstated mine plan.
| Mining segment | Indicative P/NAV | What the multiple implies |
|---|---|---|
| Royalty and streaming platforms | 1.2x–2.0x | Premium for capital-light, diversified cash flow |
| Copper majors | 1.1x–1.2x | Scale and quality, but full operating and capex exposure |
| Mid-tier copper producers | 0.5x–0.8x | Greater execution, jurisdiction and balance-sheet risk |
| Gold juniors and developers | 0.4x–0.6x | Permitting, financing and construction discounts |
| Early-stage explorers | 0.3x–0.45x | High geological and development uncertainty |
| Recent M&A reference | About 0.73x deliverable NAV | Buyers paying below full NAV for execution risk |
Gold equities remain a notable valuation anomaly. Many models continue to use long-term gold assumptions of approximately US$2,200–US$2,400 per ounce, well below spot levels around US$4,300. As a result, gold equities can trade at an estimated 40% discount to modeled NAV even when current revenue is benefiting from higher prices.
The gap is not automatically an opportunity. Analysts still need to test whether costs, sustaining capital, taxes, royalties and mine lives have been normalized. A transaction at 0.73x deliverable NAV may represent disciplined buying, or a recognition that the published NAV is not fully financeable.
Commodity markets: the catalysts behind asset values
Copper is trading near record levels, with LME copper around US$14,637 per tonne and SHFE copper near CNY110,775 per tonne. Three-month copper recently reached about US$14,703 per tonne before pulling back as exchange inventories rebuilt.
The near-term swing factor is the expected U.S. Section 232 copper tariff decision, while treatment and refining charges remain at or below zero. Low charges signal tight concentrate availability and strengthen the earnings outlook for producers with payable copper, although stockpiling must be separated from genuine end-user consumption.
Lithium carbonate futures are around CNY132,500 per tonne after a 4% move, with spot indications in a broad RMB140,000–185,000 per tonne range. Chinese inventories are approximately 175,000 tonnes. The Jianxiawo restart and fourth-quarter battery demand are the key variables.
Nickel is near US$16,000 per tonne, with Indonesian RKAB ore quotas acting as the supply floor. Uranium is around US$89.75 per pound spot and US$96.50 per pound term, while contracting activity is running ahead of a projected 2027 deficit.
Gold is around US$4,309–US$4,352 per ounce, and silver is near US$65 per ounce after the Federal Reserve raised its target range by 25 basis points to 3.75%–4.00%.
Market snapshot
| Asset | Indicative level | Investment read-through |
|---|---|---|
| LME copper | US$14,637/t | Supports cash flow for producers; tariff risk remains |
| SHFE copper | CNY110,775/t | Strong Chinese pricing, but inventories need monitoring |
| Gold | US$4,309–US$4,352/oz | Supports producer margins, while NAV models lag spot |
| Silver | About US$65/oz | Benefits silver-heavy mines and streaming portfolios |
| Lithium carbonate | CNY132,500/t futures | Restart risk versus fourth-quarter battery demand |
| LME nickel | About US$16,000/t | Indonesian quotas remain the central supply variable |
| Uranium | US$89.75/lb spot; US$96.50/lb term | Contracting supports long-term deficit narrative |
Copper scenario framework
| Scenario | Price range | Key assumptions |
|---|---|---|
| Bear | US$11,000–US$13,500/t | Inventory rebuild, weaker demand and tariff disruption |
| Base | US$12,800–US$14,500/t | Tight concentrates, steady grid demand and controlled supply |
| Bull | US$15,000–US$16,000/t | Persistent concentrate shortage, stockpiling and policy support |
Investor checklist
Before underwriting a mining investment or transaction, investors should:
- Normalize NAV using commodity prices below current spot
- Compare transaction value with deliverable, not theoretical, NAV
- Separate copper stockpiling from end-user consumption
- Review permits, metallurgy, infrastructure and remaining capex
- Track funding runway and operator liquidity
- Examine royalty step-downs, buybacks and contingent payments
- Monitor real yields and the U.S. dollar
- Follow the Section 232 decision window, Jianxiawo review and Indonesian RKAB quotas
Luca’s Cozamin deal shows how producing assets can command strategic value even when public-market multiples remain uneven. Artemis’ Mt Todd transaction shows the appeal of acquiring permitted ounces without immediately funding construction. Together, they suggest that the next phase of mining M&A will be judged less by resource size and more by cash-flow timing, infrastructure readiness and the credibility of the NAV.
LinkedIn:
Luca Mining’s proposed US$385 million Cozamin acquisition highlights a changing mining M&A test: investors are placing greater value on permitted infrastructure, near-term cash flow and deliverable NAV, not resource tonnes alone. Our latest Skillings Mining Intelligence digest examines the deal, Artemis Gold’s Mt Todd strategy, royalty-streaming terms and the commodity catalysts shaping P/NAV.
X:
Luca’s Cozamin deal puts a new marker on mining valuations. We examine the US$385M consideration, Artemis–Vista’s Mt Todd combination, royalty-streaming diligence, P/NAV ranges and the copper, lithium, nickel, uranium, gold and silver catalysts investors are watching.
Market information is provided for journalistic and educational purposes only and is not financial advice. No information in this publication should be interpreted as a recommendation to buy, sell or hold any security.
Related reading
- Luca Mining’s Cozamin operations
- Capstone Copper announces the Cozamin sale
- Artemis Gold agrees to acquire Vista Gold
- Empress Royalty’s Tongon stream announcement
- Elemental Royalty completes the Vizsla Royalties acquisition
- Skillings Mining Intelligence: Royalty streams, M&A premiums and the P/NAV test