By Salini Krishnan

Mining investors are entering the Federal Reserve decision with three competing signals: copper has retreated from a record, gold and silver remain sensitive to higher yields, and royalty companies continue to use premium valuations to pursue long-term commodity exposure.
The FOMC statement is due at 2 p.m. ET, with markets pricing roughly 90%–93% odds of a 25-basis-point hike. Chair Kevin Warsh’s guidance and the updated dot plot are likely to matter more than the rate decision itself. A hawkish message could raise the opportunity cost of holding bullion and pressure development-stage mining equities. A less restrictive signal could help narrow the valuation gap between spot metals and mining shares.
For operators and investors, the central question is not simply whether a commodity is expensive or cheap. It is whether the underlying asset can convert its resource, permitting position and infrastructure into deliverable cash flow.
Market snapshot
| Commodity or indicator | Latest reference | Investment read-through |
|---|---|---|
| LME copper | US$14,084/t | Retreating from the September record near US$14,854/t; tariff positioning remains important |
| SHFE copper | CNY107,740/t | Chinese pricing remains a test of physical demand and inventory conditions |
| Gold | US$4,342–4,344/oz | Up about 1.2%, but exposed to yields, the dollar and Fed guidance |
| Silver | US$64.55/oz | Up about 1.6%; industrial demand and monetary flows remain important |
| Lithium carbonate | RMB140,000–185,000/t | Inventory methodology and the Jianxiawo restart are key variables |
| LME nickel | About US$16,000/t | Indonesian RKAB quotas remain the principal supply constraint |
| SHFE nickel | CNY122,040/t | Chinese demand and refined-market conditions remain mixed |
| Uranium | About US$90/lb | Term-market strength continues to support longer-cycle development interest |
Copper’s move is especially important because the market must distinguish genuine end-user consumption from stockpiling ahead of the U.S. Section 232 decision window on Sept. 30. Skillings’ copper tariff analysis examines how policy uncertainty has affected U.S. premiums and producer equities.
P/NAV gaps are investigation triggers
Royalty and streaming companies continue to trade at approximately 1.2x–2.0x P/NAV, well above most conventional mining equities. Copper majors are generally around 1.1x–1.2x, while mid-tier copper companies trade near 0.5x–0.8x.

Gold juniors and developers sit around 0.4x–0.6x P/NAV, with early-stage explorers closer to 0.3x–0.45x. Gold equities carry an estimated 40% discount partly because valuation models still use long-term gold assumptions of approximately US$2,200–2,400/oz, even with spot prices above US$4,300/oz.
Recent M&A has been clearing at roughly 0.73x deliverable NAV. That benchmark is useful, but it does not mean every low-multiple company is undervalued. A discount may reflect permitting delays, difficult metallurgy, weak infrastructure, high capital intensity, jurisdictional exposure or limited balance-sheet runway.
| Segment | Indicative P/NAV | What investors must verify |
|---|---|---|
| Royalty and streaming platforms | 1.2x–2.0x | Portfolio diversification, counterparty quality and production visibility |
| Copper majors | 1.1x–1.2x | Mine-life replacement, cost position and project execution |
| Mid-tier copper | 0.5x–0.8x | Infrastructure, financing and development milestones |
| Gold juniors and developers | 0.4x–0.6x | Permits, metallurgy, capex and funding runway |
| Early-stage explorers | 0.3x–0.45x | Discovery quality, drilling evidence and capital access |
| Recent M&A reference | ~0.73x deliverable NAV | Whether NAV is actually deliverable on a credible schedule |

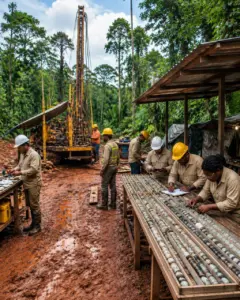
Copper mineralization must still pass technical, permitting and financing tests before it becomes deliverable NAV.
Royalty deal flow shows where capital is moving
Recent transactions show continued demand for royalties and streams covering copper, gold and silver assets.
Elemental Royalty completed its acquisition of Vizsla Royalties for approximately C$327 million, comprising up to C$82 million in cash and about 8.1 million Elemental shares. Vizsla holders received approximately 11.19% of Elemental. The transaction secures 2.0%–3.5% life-of-mine NSRs over the Panuco silver-gold project in Mexico.
Franco-Nevada agreed to pay A$170 million to increase its Bullabulling gold royalty interest to approximately 3.90%, alongside a A$30 million equity subscription in Minerals 260. The combined package is valued at A$200 million.
Vox Royalty completed an A$8.4 million acquisition of the White Dam, Kalman and Sylvania Australian gold and copper royalties. Smaller portfolio additions can be meaningful when they diversify production and extend future optionality.
Chancery Royalty signed a non-binding term sheet for a US$20 million royalty financing with Fulcrum Metals. The proposed structure would secure a 5% NSR on gold production from the Teck-Hughes project in Ontario, linked to cyanide-free recovery from historic mine waste.
Silver Crown Royalties completed its third 1% NSR acquisition on the Madre Sierra deposit within Peru’s Titiminas project for US$3 million in cash and units.
Mako Mining signed a non-binding letter of intent with Sailfish Royalty for a 20-year gold purchase agreement. Because the arrangement is non-binding, funding, final terms and completion risk remain material considerations.
The common thread is flexible capital. Royalty companies can fund project owners without taking direct responsibility for mine construction, labour, energy costs or sustaining capital. But they remain exposed to delayed production, operator liquidity, contract enforceability and changing mine plans.
M&A buyers are paying for access, not just tonnes
Recent M&A activity reinforces the same message. Lahontan Gold has agreed to acquire Emergent Metals, consolidating full ownership of the West Santa Fe project, eliminating associated royalties and adding the New York Canyon copper-gold-silver-molybdenum system.
Vizsla Copper is acquiring Agnico Eagle’s Delta polymetallic VMS and Helm Bay gold projects for approximately C$32 million. Agnico is expected to take about 19.99% of Vizsla, potentially rising to 22% pending approval.
Other transactions include First Au’s proposed all-scrip takeover of Javelin Minerals, Rokmaster Resources’ progress toward 100% ownership of the Cristal porphyry copper project in Chile, and Krait Critical Minerals’ acquisition of Nevada Hills Antimony and two Washington projects.
5E Advanced Materials received bankruptcy court approval to acquire Searles Valley Minerals’ operating assets, including borate and soda ash infrastructure, through a Section 363 sale. Asia Broadband closed a US$5.5 million acquisition of the La Vencedora gold and silver mine in Mexico. Evolution Mining increased its interest in Nevada North lithium to 32.5%, while Austral Resources made a binding A$80.7 million bid for Hammer Metals, including the Kalman copper-gold deposit.
These transactions indicate that buyers are paying for districts, processing routes, infrastructure, permitting status and strategic optionality. Headline resource tonnes are only the starting point.
Copper scenarios hinge on policy and physical flows
Citi holds a bullish three-month copper target near US$15,000/t, but the forecast depends heavily on whether the U.S. tariff premium persists.
| Scenario | Copper range | Main assumptions |
|---|---|---|
| Bear | US$11,000–13,500/t | Tariff delay, U.S. stockpile release, softer Chinese demand and stronger scrap flows |
| Base | US$12,800–14,500/t | Physical tightness persists while the policy premium moderates |
| Bull | US$15,000–16,000/t | Tariffs are implemented and ex-U.S. inventories tighten |
The most useful indicators are warehouse withdrawals, regional premiums, scrap flows, Chinese imports and cash-to-three-month spreads. A decline in U.S. inventories may not represent new consumption if metal is simply being moved ahead of a tariff.
Skillings’ copper price forecast coverage provides additional context on the relationship between tariff timing, stockpiling and mine-supply constraints.
Lithium and nickel remain supply-policy markets
Lithium prices weakened after a methodology change lifted reported Chinese inventories to about 175,000 tonnes. Macquarie has described the move as information-driven rather than evidence of a sharp fundamental deterioration.
The working carbonate range remains RMB140,000–185,000/t. The Jianxiawo restart and fourth-quarter battery demand are the main variables. Skillings’ lithium supply outlook details how environmental approvals and mine timing can remove expected supply without eliminating long-term capacity.
Nickel is trading around US$16,000/t on the LME, with a broader scenario range of US$17,000–19,000/t. Indonesian RKAB ore quotas remain the supply floor. For nickel developers, the relevant question is whether policy-controlled supply can tighten the market faster than new capacity and weaker demand can offset it.
The Fed test for gold, silver and mining equities
Gold is up about 1.2% near US$4,343/oz, while silver is up roughly 1.6% near US$64.55/oz. However, the opportunity cost of holding bullion has increased as the 10-year Treasury yield moved above 5%.
Goldman Sachs retains a year-end gold view near US$4,900/oz, while J.P. Morgan continues to prioritize gold and copper in its 2026 sector preferences. Those constructive views face a near-term test from the Fed’s dot plot, Chair Warsh’s guidance and the path of real yields.
The risk for mining equities is that high spot prices do not automatically produce higher P/NAV multiples. Investors may continue to discount companies using conservative long-term price decks, particularly where capital requirements and permitting remain uncertain.

Precious-metals valuations depend on both bullion prices and the credibility of future mine cash flow.
Investor checklist
- Treat a low P/NAV as a diligence trigger, not proof of undervaluation.
- Test NAV using normalized commodity prices below spot.
- Separate copper stockpiling from genuine end-user consumption.
- Review permits, metallurgy, infrastructure, water and power access.
- Compare transaction value with deliverable NAV rather than headline resource size.
- Check royalty step-downs, buyback rights and future exploration coverage.
- Assess operator balance sheets and funding obligations.
- Track the Fed’s dot plot, real yields and the dollar alongside metal prices.
- For lithium and nickel, monitor regulatory decisions and supply quotas.
- Prefer measurable development milestones over resource growth alone.
Social snippets
LinkedIn:
Mining valuations are sending two different signals: royalty and streaming platforms trade around 1.2x–2.0x P/NAV, while many copper, gold and lithium developers remain below 0.8x. Our latest Skillings Mining Intelligence examines royalty deal flow, M&A benchmarks, copper tariff scenarios and the Fed test for precious-metals equities.
X:
P/NAV gaps remain wide across mining. Royalty platforms trade at a premium while developers face permitting, capex and funding discounts. We examine copper scenarios, lithium and nickel supply risks, royalty deal flow and the Fed’s next test for gold and silver.
Market information is provided for journalistic and educational purposes only. It is not financial advice or a recommendation to buy, sell or hold any security, commodity or financial instrument.