

Standfirst: An industry-backed study projects higher exploration investment and accelerated mine development if Canada broadens tax eligibility for feasibility work. The potential gains depend on policy design, investor response and whether additional exploration leads to commercially viable mines.
Canada could attract an additional C$700 million to C$1.6 billion in annual mineral exploration spending under an expanded tax-incentive framework, according to an economic impact assessment prepared by EY-Parthenon for the Association for Mineral Exploration (AME).
Released in October 2026, the study examines how changes to Canadian Exploration Expenses (CEE) eligibility and the Mineral Exploration Tax Credit (METC) could influence exploration investment, employment and mine development. Its high-impact scenario estimates up to C$33 billion in cumulative economic impact from increased exploration spending and the potential advancement of three to five additional mines.
These are modelled outcomes rather than guaranteed gains. The study was commissioned by AME, which advocates broader tax eligibility, and relies on assumptions about investment, commodity markets and project development. Its findings provide an economic case for reform, but do not establish that the proposed changes will deliver the projected results.
The Financing Gap Between Discovery and Development
Canadian mineral exploration companies, particularly junior miners, rely heavily on equity financing to fund geological surveys, drilling and technical studies before a deposit demonstrates commercial viability.
More Read
Flow-through shares support this financing model by allowing eligible resource companies to transfer qualifying expenses to investors, who can deduct those expenditures against taxable income. Eligible investors may also qualify for additional tax credits, subject to the applicable rules.
The classification of expenditure matters because Canadian Exploration Expenses can generally be deducted immediately, while Canadian Development Expenses are generally deducted at 30% on a declining-balance basis. The tax treatment can influence the cost of raising capital and the timing of investment in mineral projects.
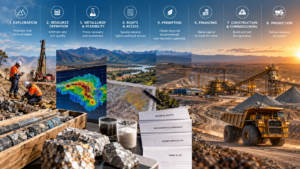
Engineering-feasibility and economic-viability studies are critical to determining whether a discovery can support a mine. However, these costs have generally been excluded from CEE under the Canada Revenue Agency’s interpretation of the existing rules.
More Read
AME argues that extending eligibility to qualifying technical and feasibility work would help junior companies finance the transition from discovery to development. This stage can require substantial expenditure before a project generates revenue or attracts construction financing.
What the EY Scenarios Estimate
EY-Parthenon’s high-impact scenario combines broader CEE eligibility for feasibility and economic-viability studies with an extension of the METC to 2035. It also assumes supportive commodity-market conditions and a more favourable environment for advancing mineral projects.
Under this scenario, the study estimates an additional C$700 million to C$1.6 billion in annual exploration expenditure compared with its base case. It attributes a 10% to 15% increase in exploration spending to broader CEE eligibility, with an additional 5% to 10% increase in early-stage exploration spending associated with extending the METC. These are modelled estimates, not observed results.
The study estimates C$5.2 billion to C$12.2 billion in additional GDP over 2026–2035 from increased exploration spending. It also projects 14,000 to 34,000 additional full-time-equivalent person-years of employment across the Canadian economy over the same decade. These are cumulative employment units, not an equivalent number of permanent jobs created and maintained.
A separate component estimates that three to five additional mines could be accelerated or advance into development and operations. These projects could contribute C$12.9 billion to C$21.4 billion in incremental GDP over their construction and operating lives.
Combining the upper estimates produces approximately C$33.6 billion in cumulative economic impact, which AME summarises as up to C$33 billion. The figure combines exploration-related benefits over ten years with potential mine-development benefits over longer periods. It is neither an annual GDP increase nor a guaranteed return on government spending.
Policy Status and Tax-Credit Uncertainty
Budget 2025 proposed clarifying that expenses incurred to determine a mineral resource’s engineering feasibility or economic viability are excluded from CEE. The federal government subsequently advanced this clarification through its legislative process.
The broader expansion sought by AME is a separate policy proposal. The association advocates changing the treatment of qualifying technical studies so that more project-advancement work can benefit from flow-through share financing.
The METC is also distinct from the Critical Mineral Exploration Tax Credit (CMETC). The METC provides a 15% non-refundable credit for specified eligible exploration expenses, while the CMETC provides a 30% credit for qualifying expenses associated with eligible critical minerals.
Government materials identify March 31, 2027, as the current deadline for eligible METC flow-through share agreements. The study’s scenario assumes an extension to 2035; that extension should not be treated as enacted policy. The final eligibility rules, effective dates and interaction with flow-through share financing will determine how much additional capital companies can raise.
For exploration companies and investors, the distinction between existing rules, proposed changes and scenario assumptions is important. A policy commitment or industry recommendation does not automatically change which expenditures qualify for tax treatment.
Fiscal Costs and the Additionality Test
EY estimates approximately C$6.6 billion in foregone tax revenue over ten years under its enhanced-incentive scenario, equivalent to an average of about C$660 million annually. The study also estimates additional tax receipts associated with higher economic activity.
These projections do not establish that the incentives will pay for themselves. The results depend on assumptions about investment behaviour, commodity prices, permitting, infrastructure and future mine development. The reported economic impacts also include direct, indirect and induced activity.
The central policy question is additionality: how much new exploration and project-advancement work would the incentives generate that would not otherwise occur? Some companies might use broader eligibility to finance genuinely additional technical work, while others could obtain favourable tax treatment for expenditure they would have undertaken anyway.
There is also a conversion risk. Higher exploration spending does not guarantee economic discoveries, successful permitting, infrastructure access or the financing required to construct a mine. Projects can remain uneconomic even after substantial technical work, particularly if commodity prices weaken or development costs rise.
The reform’s effectiveness will therefore depend on whether it improves access to capital for viable projects and accelerates investment decisions that would otherwise be delayed—not simply on the volume of tax-favoured expenditure claimed.
What Mining Investors Should Watch
The next indicators are the final legislative treatment of CEE eligibility, the duration and scope of any METC extension, and the response from exploration companies and flow-through share investors. Evidence of additional financing, completed feasibility studies and projects advancing towards construction would provide a stronger measure of policy effectiveness than projected expenditure alone.
For Canada’s critical minerals sector, broader tax eligibility could help address the financing gap between discovery and development. But the projected C$1.6 billion in annual exploration spending and up to C$33 billion in cumulative economic impact remain conditional outcomes under EY-Parthenon’s high-impact scenario.
The decisive test will be whether the reform generates genuinely additional investment, advances commercially viable deposits and strengthens Canada’s pipeline of mines capable of reaching production.
Use up and down arrow keys to resize the meta box pane.