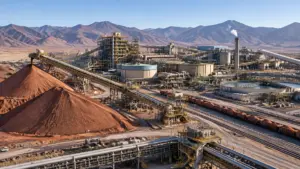
Copper concentrate stockpiled beside material-handling equipment at a smelting facility.

By Mo Shine
The copper concentrate market has reached a point that would have been difficult to imagine only a few years ago: the 2026 annual treatment and refining charge benchmark settled at US$0 per dry metric tonne and 0 cents per pound.
It is the first zero settlement on record. In plain terms, miners are no longer paying a standard processing fee under the benchmark, while spot deals have moved even further. Spot TC/RCs have traded below -US$100 per dry metric tonne at times, meaning some smelters are effectively paying miners for access to concentrate.
The benchmark collapse reflects a structural imbalance. Global mine supply is constrained just as smelting capacity: particularly in China: has expanded on the assumption that concentrate would remain readily available. The result is a market in which miners hold the scarce input and smelters compete to keep furnaces operating.
Reporting from Mining.com, Mysteel and CRU shows how rapidly the traditional pricing structure is being forced to adapt.

Copper concentrate reference points
| Market indicator | 2026 reference | Why it matters |
|---|---|---|
| Annual benchmark TC | US$0/dmt | First zero annual treatment-charge settlement on record |
| Annual benchmark RC | 0 cents/lb | No benchmark refining charge deducted from payable copper |
| Indicative spot TC | Below -US$100/dmt at times | Smelters are paying to secure scarce feedstock |
| Global mine output | -1.1% in H1 | Supply contraction is tightening the concentrate market |
| Chile mine forecast | -2.6% | Guidance was cut twice amid operational weakness |
| Grasberg capacity | About 65% in H2 | A major supply disruption with full capacity targeted by end-2027 |
| LME copper record | US$5.45/lb, or about US$14,231/t | Price strength is occurring alongside concentrate scarcity |
| Contract structure | Increasingly index-linked | Pricing is moving closer to short-term market conditions |
The supply picture is unusually weak. Global copper mine production fell 1.1% in the first half, while Morgan Stanley expects the first annual decline in mine supply since 2017. Chile has cut its annual guidance twice and is forecasting a 2.6% decline. Codelco and Freeport-McMoRan have reported double-digit output drops, while Grasberg is operating at roughly 65% of capacity in the second half.
Against that backdrop, LME copper reached a record US$5.45 per pound on Sept. 16, supported by falling LME inventories and Chinese export dynamics. The price is signaling scarcity in refined metal, but TC/RCs show where the physical bottleneck is forming: upstream, at the concentrate stage.
How negative TC/RC flips the smelting model
Copper concentrate is the partially processed material produced by a mine. A smelter converts it into blister copper or anodes, which are then refined into cathode.
Under a normal market structure:
- The miner sells concentrate containing payable copper.
- The smelter deducts a treatment charge, or TC, for converting the concentrate.
- A refining charge, or RC, is deducted based on the refined copper produced.
- Additional penalties may apply for impurities, while gold, silver, molybdenum and other by-products can generate credits.
When concentrate is plentiful, smelters have negotiating power and TCs and RCs rise. When concentrate is scarce and smelting capacity is abundant, the balance reverses. Miners can demand lower charges because multiple smelters are competing for the same feedstock.
At zero TC/RC, the smelter receives no standard processing income under the benchmark. At negative TC/RC, the smelter pays for the right to process the material. The economics are reversed: the smelter is no longer charging for conversion but subsidizing access to concentrate.
This does not mean every contract carries the same negative terms. Annual agreements, spot transactions, quality adjustments and regional markets differ. However, CRU’s reporting shows that the gap between fixed contract terms and spot assessments has widened far beyond historical norms.
The first facilities likely to curtail are independent, high-cost smelters with limited by-product revenue, weak access to concentrate and high power or environmental-compliance costs. Integrated producers with captive mines can withstand the pressure longer. Efficient Chinese plants may also continue operating to preserve market share, employment and downstream supply relationships, even when copper-processing margins are weak.

Molten copper moving through a flash smelting furnace tap and casting system.
The feedback loop matters. If high-cost smelters reduce output, refined copper supply tightens. That can support copper prices, but it does not immediately solve the concentrate shortage. Instead, it transfers more value toward miners with material available to sell.
Impurities and by-products become the competitive frontier
Headline TC/RCs are only one part of smelter economics. As charges approach zero or fall below it, the value of the concentrate itself becomes more important.
Smelters will increasingly distinguish between concentrates based on:
- Copper grade and recovery rate
- Arsenic, antimony and other impurity levels
- Moisture and transport characteristics
- Gold, silver and molybdenum content
- Sulfuric acid production potential
- Blending flexibility and delivery reliability
A clean, high-grade concentrate can command materially better commercial treatment than a lower-quality product carrying elevated arsenic or antimony. Impurity penalties can erode or eliminate the advantage of a negative TC.
Blending is therefore becoming a strategic capability. Smelters that can combine different concentrates to stay within technical and environmental limits may protect throughput when individual cargoes become more difficult to process. Plants with limited blending flexibility face a narrower procurement market and greater exposure to penalties.
By-product credits also matter more when copper treatment income disappears. Gold and silver can provide a valuable revenue stream, while sulfuric acid sales can offset weak TC/RC economics. The reverse is also true: weaker acid markets or lower precious-metal recoveries can quickly expose the underlying loss on copper processing.
This is one reason the pressure is not uniform across the industry. Two smelters paying the same TC/RC may have very different financial outcomes depending on their power contracts, acid sales, impurity profile and by-product portfolio.
What zero charges mean for miners
For miners, the market is being repriced toward the upstream end of the value chain.
A lower TC means less value is deducted from payable copper. A negative TC can add a payment to the miner’s commercial terms, depending on the contract formula. The result is stronger realized pricing and improved leverage in offtake negotiations.
But the benefit is available only to producers with concentrate to sell. A mine facing lower grades, equipment failures, water constraints or shipment delays cannot fully benefit from favorable terms. High copper prices do not compensate for missing tonnes in the short term.
The strongest position belongs to producers with:
- Reliable concentrate volumes
- Low impurity levels
- Consistent logistics
- Credible production guidance
- Multiple smelter and trader relationships
The same conditions also improve the economics of new copper projects. Lower processing deductions can lift project revenue assumptions and strengthen the case for investment. Yet permitting, construction and ramp-up timelines remain long, so current pricing cannot produce immediate new supply.
For a related view on the interaction between copper prices, inventories and mine supply, see Skillings’ copper market analysis.
From annual benchmarks to market-linked pricing
The zero benchmark has also exposed a weakness in the traditional annual pricing system. A fixed number negotiated once a year becomes less useful when spot TC/RCs move sharply below it.
In April, CRU launched a weekly copper concentrate TC/RC assessment to provide a more frequent market signal. Its later reporting on mid-year settlements described a growing shift toward index-linked and hybrid structures.
Under an index-linked agreement, the TC/RC moves with an agreed market assessment rather than remaining fixed. That gives miners more exposure to scarcity when spot terms are negative, while giving smelters a formula that can adjust if concentrate availability improves.
The change creates more volatility for both sides. Miners may capture higher prices in a tight market but face faster deterioration when supply recovers. Smelters gain a more transparent reference but lose the protection of long-term terms set above the prevailing spot market.
The fixed annual benchmark may remain as a reference point, but its influence could decline as more tonnes move into short-term, index-linked or hybrid contracts.
Scenario framework
The following framework is analytical rather than an investment recommendation. It focuses on concentrate tightness and refined copper prices as the market moves toward 2027.
| Scenario | Concentrate market | Refined copper range | Key conditions |
|---|---|---|---|
| Bear case | Tightness eases | US$3.90–US$4.75/lb | Mine recovery, weaker Chinese demand, stronger scrap supply and smelter curtailments reduce competition for feed |
| Base case | Tight but functioning | US$4.75–US$5.50/lb | Mine disruptions persist, new supply remains limited and grid demand offsets weaker construction |
| Bull case | Severe deficit | US$5.50–US$6.25/lb | Further mine outages, delayed projects, resilient electrification demand and negative spot TC/RCs continue |
Bear case
The bear case requires concentrate availability to improve faster than expected. Grasberg would need to return toward normal operations, Chilean output would need to stabilize and new or expanded mines would need to deliver reliably.
A slowdown in Chinese manufacturing or a sharp increase in scrap collection could also reduce demand for primary concentrate. Under that scenario, smelters would regain bargaining power and TC/RCs would recover from extreme lows.
Base case
The base case assumes continued scarcity without a complete breakdown in refined supply. Copper prices remain elevated, but demand is uneven across construction, manufacturing, grids, electric vehicles and data-center infrastructure.
TC/RCs remain historically weak, with a larger share of contracts linked to market assessments. Smelters continue operating, but high-cost facilities face maintenance delays, output cuts or pressure to consolidate.
Bull case
The bull case combines another major mine disruption with resilient demand. If Grasberg’s recovery is delayed, Chilean production weakens further or other large operations underperform, the concentrate deficit could deepen.
In that environment, negative spot TC/RCs would persist, refined inventories would remain vulnerable and copper prices could move above the current record zone. The greatest pressure would fall on Western smelters and other facilities dependent on imported concentrate without strong by-product credits.
What to watch next
The most useful indicators will be physical-market data rather than copper prices alone:
- Quarterly TC/RC settlements and the share of contracts using index-linked formulas
- Chinese smelter output, maintenance schedules and announced curtailments
- Codelco and Freeport-McMoRan production updates
- Grasberg’s capacity recovery
- LME and SHFE inventories, including warehouse cancellations
- Concentrate impurity penalties and blending requirements
- Gold, silver, molybdenum and sulfuric acid by-product prices
The zero benchmark is more than a record-low fee. It is evidence that the copper value chain is being reorganized around a scarce input. Miners with concentrate are capturing a greater share of the metal’s value, while smelters must compete on efficiency, blending, by-products and feedstock security.
The central question for 2027 is whether new mine supply can arrive quickly enough to restore balance. Until then, negative TC/RCs remain one of the clearest signals that copper’s tightness begins before the smelter gate.
Social snippets
LinkedIn:
Copper’s 2026 annual concentrate benchmark settled at US$0/dmt TC and 0 cents/lb RC: the first zero settlement on record. Spot charges have traded below -US$100/dmt, reversing the normal smelter business model. Our analysis examines why miners are capturing the margin, which smelters face curtailment first, and how index-linked pricing could reshape the copper market.
X:
Copper concentrate fees have reached an historic zero benchmark, while spot TC/RCs have fallen below -US$100/dmt. Mine supply is tight, smelter capacity is competing for feed and pricing is shifting toward indexes. We break down the implications for miners, smelters and copper prices.