By Charles Pitts

Mining M&A in 2026 is increasingly being shaped by a question that sits beside resource size and commodity exposure: how reliably can the asset move through permitting, regulatory review and construction?
That shift is visible across transactions involving nickel, lithium, gold, silver, copper and rare earths. Buyers are still pursuing strategic resources, but the strongest targets are often projects with established infrastructure, a defined regulatory pathway, existing technical data or a clear route to production.
The result is a market in which permitting certainty has become a form of deal value. It can reduce the time to first production, improve financing prospects and lower the risk that a promising deposit remains stranded in development.
The pattern is not uniform. Luca Mining’s acquisition of El Barqueño shows that buyers will still take on permitting risk when the geological database, infrastructure and regional strategy are compelling. MMG’s proposed purchase of Anglo American’s Brazilian nickel assets shows the other side of the equation: even a strategically important producing business can face prolonged scrutiny when supply-chain concentration becomes a regulatory concern.
More Read
Selected mining M&A transactions
The table below tracks disclosed transaction values, bid structures and reported status across the deals shaping the 2026 market.

| Bidder or buyer | Target or assets | Jurisdiction | Bid or deal value | Status |
|---|---|---|---|---|
| MMG | Anglo American’s Brazilian nickel assets | Brazil / European Union | Up to US$500 million | European Commission objection; decision due by Nov. 30 |
| Luca Mining | El Barqueño gold-silver-copper project from Agnico Eagle | Mexico | Up to US$60 million | Definitive agreement; closing subject to approvals |
| Lahontan Gold | Emergent Metals, including West Santa Fe and New York Canyon | Nevada, United States | About C$7.8 million | Arrangement agreement; shareholder, court and regulatory approvals pending |
| Huayou Cobalt | Atlantic Lithium and the Ewoyaa project | Australia / Ghana | About US$210 million | Australian foreign-investment clearance obtained; other approvals pending |
| First Au | Javelin Minerals’ Eastern Goldfields portfolio | Western Australia | About A$46.5 million implied value | Recommended all-scrip takeover; minimum acceptance condition applies |
| China Rare Earth Group | Shenghe Resources | China / United States exposure | Undisclosed | Reported talks; no definitive transaction announced |
| Newmont and Barrick | Fourmile, Fiberline and Mike projects added to Nevada Gold Mines | Nevada, United States | US$1.95 billion cash from Newmont to Barrick | Agreement reached; JV expansion and governance changes announced |
| Canada Investment Summit | Broad investment commitments, including critical minerals | Canada | Nearly C$500 billion headline commitment | Sector-wide financing capacity; much remains conditional and non-binding |
Values and statuses are based on company announcements and reported information available at the time of writing.
Buyers are acquiring time as much as tonnes
The most valuable feature of an advanced mining asset may not be its resource estimate alone. It may be the amount of uncertainty already removed from the development schedule.
Permits, environmental studies, Indigenous consultation, land access, infrastructure and community agreements all affect the time between acquisition and production. Delays can increase capital costs, weaken project economics and leave developers exposed to changes in commodity prices or government policy.
This is why advanced projects can attract strategic interest even when they are smaller than early-stage discoveries. In a market where discovery-to-production timelines can stretch for decades, a project with a clearer pathway can offer a more measurable development schedule.
The trend is particularly important for critical minerals. Governments may announce large pools of capital, but lenders and strategic buyers still need projects that can reach construction and production. Canada’s Investment Summit claimed nearly C$500 billion in new commitments across infrastructure, energy, technology, defense and resources. Yet analysis from RBC noted that permitting, infrastructure and project economics remain significant constraints.
The gap between announced capital and bankable mine finance is therefore becoming a central M&A issue.

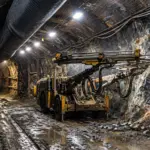
Nickel ore in an underground mining environment.
MMG’s nickel deal shows the geopolitical limit
MMG’s proposed US$500 million acquisition of Anglo American’s Brazilian nickel assets is a clear example of why ownership, supply chains and permitting now overlap.
The European Commission has issued a Statement of Objections over concerns that the transaction could restrict competition in the low-carbon ferronickel market. European stainless-steel producers have limited alternative sources, and regulators are examining whether the assets’ output could be redirected away from European customers.
MMG has pledged to maintain or increase supplies to Europe and has indicated that it is willing to enter long-term supply agreements with European buyers. The Commission is expected to reach a decision by Nov. 30, either clearing the transaction, approving it with remedies or prohibiting it.
The case, reported by Reuters, demonstrates that producing assets do not automatically provide transaction certainty. The asset may be operationally de-risked, but the buyer’s ownership, affiliations and downstream relationships can create a new layer of regulatory risk.
For critical-mineral buyers, permitting diligence now extends beyond mine approvals. It also includes competition policy, foreign investment review, customer concentration and the political geography of supply.
Mid-tier consolidation favors established districts
Several smaller and mid-tier transactions show a different form of de-risking: consolidating land, data and infrastructure within an existing operating region.
Luca Mining’s agreement to acquire El Barqueño from Agnico Eagle is valued at up to US$60 million, including initial, milestone and production-linked consideration. The project is Luca’s third Mexican property and covers more than 32,000 hectares in Jalisco.
Agnico Eagle completed approximately 225,000 metres of drilling at the project, contributing to a substantial geological database. Luca has described the property as having road access, existing infrastructure and potential for both open-pit and underground mining.
But the transaction also illustrates why due diligence cannot treat “advanced” as synonymous with “permitted.” El Barqueño is not currently permitted for exploration drilling because of a land-use planning dispute involving the Jalisco Regional Ecological Territorial Planning Program. Luca intends to pursue a legal pathway to clarify the project’s exploration and development route.
The project therefore offers geological and regional certainty, but not complete permitting certainty. That distinction is important for buyers and investors assessing the real time to value.
In Nevada, Lahontan Gold’s acquisition of Emergent Metals is more directly focused on ownership simplification. The all-share transaction would give Lahontan full ownership of West Santa Fe, eliminate a 1% net smelter return royalty on West Santa Fe and the York claims, and add the adjacent New York Canyon project.
The approximately C$7.8 million deal also consolidates Lahontan’s position around its Santa Fe Mine. In this case, the strategic value lies in reducing boundary, royalty and ownership complexity across a contiguous land package.
Critical minerals remain strategic, but control is contested
Huayou Cobalt’s proposed acquisition of Atlantic Lithium provides another example of a buyer paying for a defined strategic pathway. The approximately US$210 million all-cash transaction would give Huayou control of Atlantic Lithium and the Ewoyaa lithium project in Ghana.
Australia’s Foreign Investment Review Board has cleared the transaction, satisfying an important condition. Shareholder, court and additional Ghanaian, Chinese and regional approvals remain outstanding.
As reported in Skillings’ coverage of the Huayou-Atlantic Lithium transaction, Huayou has also committed to sole-fund remaining development costs through its arrangements around Ewoyaa. That commitment can reduce financing risk and give the buyer greater control over the construction timetable.
The reported talks between China Rare Earth Group and Shenghe Resources show how geopolitical considerations are extending beyond project ownership. Shenghe owns about 3% of MP Materials, a U.S. rare earths producer. If China Rare Earth Group were to gain control of Shenghe, that indirect exposure would likely attract additional scrutiny because of MP Materials’ importance to U.S. strategic supply chains.
The development remains at the discussion stage, and Shenghe’s controlling shareholder has reportedly denied plans to transfer control. It nevertheless shows why rare earths transactions are being assessed through both a commercial and national-security lens. Skillings’ analysis of the Shenghe and MP Materials supply-chain question provides additional context.

Processing infrastructure remains a major source of value in mining transactions.
Scale is still valuable when it reduces complexity
First Au’s all-scrip takeover of Javelin Minerals combines four Eastern Goldfields gold projects near Kalgoorlie into a larger regional platform.
The transaction offers Javelin shareholders approximately 11.7647 new First Au shares for each Javelin share. On the 10-day VWAP basis, the offer represents a 40.6% premium, while Javelin shareholders would own about 48.7% of the enlarged company if the offer is fully accepted.
The combined portfolio contains approximately 350,600 ounces of gold resources across the Gimlet, Eureka and Coogee projects, with Riverina East providing additional exploration exposure. The strategic logic is less about acquiring a single large discovery than about assembling a coherent group of brownfield assets in a mature gold district.
The Newmont-Barrick agreement follows the same principle at a much larger scale. Newmont will pay Barrick US$1.95 billion in cash as Fourmile, Fiberline and Mike are brought into Nevada Gold Mines. Barrick remains the operator and majority owner, while the agreement updates governance and resolves disputes over previously excluded projects.
The transaction turns separate growth assets into part of a roughly 100-million-ounce Nevada gold complex. It also illustrates how joint ventures can provide a route to scale without requiring a full corporate takeover.
Base, bull and bear framework for mining M&A
The following framework is designed to assess the direction of mining M&A without relying on explicit investment recommendations.
| Scenario | Operating conditions | Likely M&A behavior | Key indicators |
|---|---|---|---|
| Base case | Commodity prices remain supportive but uneven; permitting and foreign-investment reviews stay lengthy | Buyers favor advanced, brownfield and infrastructure-rich assets; mid-tier consolidation continues | More milestone-based consideration, regional consolidation and long-term offtake agreements |
| Bull case | Gold, copper and critical-mineral prices strengthen while policy support accelerates approvals | Large producers pursue strategic resources and permitted projects at higher premiums | Faster approvals, stronger project finance, more competitive bids for near-production assets |
| Bear case | Commodity prices weaken, capital costs rise and regulatory reviews intensify | Deal activity shifts toward distressed assets, earn-ins and all-share structures | Wider valuation gaps, deferred payments, failed approvals and longer transaction timelines |
The most important variable across all three scenarios is not simply resource size. It is the buyer’s confidence that the asset can progress from ownership to permitting, construction and cash flow.
The new M&A checklist
Mining M&A in 2026 is becoming a contest for certainty. Buyers are evaluating:
- the status and durability of exploration and operating permits;
- Indigenous and community agreements;
- infrastructure access and power availability;
- exposure to foreign-investment and competition reviews;
- customer concentration and supply-chain commitments;
- royalties, earn-outs and contingent consideration;
- the credibility of the development timetable.
The resource race has not ended. Copper, lithium, nickel, gold, silver and rare earths remain central to corporate strategy and energy-transition planning. But a large resource without a reliable route to production can be less valuable than a smaller asset with clearer approvals, established infrastructure and a credible operator.
That is the defining lesson of the current deal cycle: in mining M&A, companies are no longer buying only what is in the ground. Increasingly, they are buying the time, permissions and operating context required to bring it out.