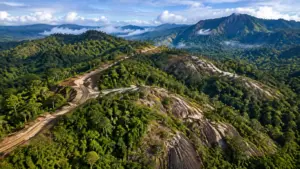
Brazilian nickel mine and processing infrastructure surrounded by lateritic terrain and forest.

MMG’s proposed $500 million purchase of Anglo American’s Brazilian nickel assets is facing another hurdle, with European regulators expected to formally set out competition concerns about the deal, according to people familiar with the matter cited by Reuters.
The European Commission is preparing a statement of objections : a formal document outlining preliminary antitrust concerns : over the transaction. The warning would not represent a final prohibition, but it would place pressure on MMG to offer stronger remedies if it wants to secure approval.
At the center of the case is ferronickel, an important feedstock for stainless-steel production. EU officials are examining whether the deal could give MMG greater influence over a concentrated supply segment and create incentives to redirect material away from European buyers.
The Commission’s concerns carry wider significance for mining M&A deals in 2026. Regulators are increasingly assessing transactions not only through conventional market-share tests, but also through the lens of supply-chain security, ownership structures and access to critical industrial inputs.
Why Brussels is examining the transaction
The proposed acquisition covers Anglo American’s Brazilian nickel business, including the operating Barro Alto and Codemin ferronickel operations, as well as the Jacaré and Morro Sem Boné development projects.

Anglo American agreed to sell the portfolio to MMG Singapore Resources, a wholly owned subsidiary of MMG, for up to $500 million. The consideration includes $350 million in upfront cash, up to $100 million linked to realized nickel prices and a further $50 million tied to investment decisions on the development projects, according to company disclosures.
Anglo’s decision formed part of a broader portfolio reshaping focused on copper, iron ore and crop nutrients. For MMG, the transaction would establish a Brazilian operating presence and expand its exposure to nickel, a metal linked to stainless steel, batteries and the broader energy transition.
The transaction is registered as European Commission merger case M.11944. The case is in Phase II, the Commission’s more detailed investigation stage, and the official case page lists a provisional deadline of Nov. 30, 2026.
The regulator has already rejected an earlier remedy proposal that would have required Anglo to purchase ferronickel from MMG for resale in Europe for as long as 10 years. The proposed arrangement was intended to preserve European supply at volumes comparable with existing sales, but it did not resolve the Commission’s concerns.
European regulators are now assessing whether a new owner could reduce or alter the flow of ferronickel to the region. The analysis is particularly sensitive because MMG is controlled by China Minmetals, giving the transaction a geopolitical dimension beyond the ownership of two Brazilian operating assets.
The Commission has previously warned that the deal could jeopardize reliable access to ferronickel for European stainless-steel producers. MMG has maintained that the transaction does not raise competition concerns in the EU and should be cleared without conditions.

Industrial processing equipment used in the production of nickel-bearing material.
The deal at a glance
| Item | Detail |
|---|---|
| Buyer | MMG Singapore Resources, part of MMG |
| Seller | Anglo American |
| Assets | Barro Alto, Codemin, Jacaré and Morro Sem Boné |
| Consideration | Up to $500 million |
| Upfront payment | $350 million |
| Contingent payments | Up to $100 million linked to nickel prices and $50 million linked to project investment decisions |
| EU case | M.11944, Phase II merger review |
| Main regulatory concern | Potential impact on ferronickel supply to European stainless-steel producers |
Source: Anglo American, MMG and the European Commission.
Nickel market outlook adds to the uncertainty
The antitrust dispute comes as the nickel market approaches a potentially more balanced phase, although forecasts remain sharply divided.
Nickel supply expanded rapidly in recent years, led by Indonesian production of nickel pig iron, ferronickel and intermediate products. That growth pushed inventories higher and placed sustained pressure on prices. Stainless steel remains the largest source of nickel demand, while battery demand has grown more slowly than many earlier forecasts anticipated because of the expansion of lithium-iron-phosphate battery chemistries.
Forecasts for the 2026 nickel market outlook range from a modest deficit to a substantial surplus:
| Market view | 2026 balance | Main driver |
|---|---|---|
| International Nickel Study Group | Deficit of roughly 32,000 tonnes | Demand growth outpaces constrained production |
| Nornickel | Surplus of about 20,000 tonnes | Near-balance as supply growth slows |
| Sumitomo Metal Mining | Surplus of roughly 256,000 tonnes | Continued Indonesian supply and moderate demand |
| ING | Surplus and range-bound prices | High inventories and stainless-steel demand risks |
The divergence is important for MMG’s proposed acquisition. In a surplus market, ferronickel producers may face weak pricing and limited negotiating power. In a tighter market, however, access to reliable material can become strategically more valuable to stainless-steel manufacturers.
The latest market estimates are discussed in Skillings’ nickel market outlook for 2026. A separate Sumitomo Metal Mining forecast also points to continued surplus conditions, while ING has highlighted the role of excess supply and inventories.
For the EU, the issue is not simply whether nickel is abundant globally. The Commission is examining whether European buyers can continue to access a specific form of nickel, from a limited group of suppliers, on reliable commercial terms.
What MMG could offer next
A statement of objections gives the parties an opportunity to respond before the Commission reaches a final decision. MMG could submit revised behavioral remedies, offer longer-term supply commitments or agree to safeguards around European customers.
The regulator could also seek more structural measures if it concludes that commercial commitments would not adequately address the risk. Those could include supply guarantees administered by an independent trustee, ring-fencing arrangements or other restrictions on how material is marketed.
The difficulty is that the commercial value of the acquisition depends partly on MMG controlling and integrating the Brazilian assets. Remedies that limit its ability to direct output could reduce the strategic rationale of the transaction.
A prohibition remains possible if the Commission determines that the proposed remedies do not resolve the competition concerns. The parties have already extended the transaction’s long-stop date while the regulatory process continues.
Investor lens: strategic logic versus execution risk
For Anglo American, the transaction would complete its exit from Brazilian nickel and provide additional capital for its preferred commodities. The $500 million headline value is modest relative to the group’s overall portfolio, but the sale helps simplify a business that has been under pressure from weaker nickel prices and operational challenges.
For MMG, the acquisition is more strategic. It would diversify the company’s production base beyond its existing copper, zinc and lead exposure and give it access to a Brazilian operating platform. The deal could also provide optionality through Jacaré and Morro Sem Boné if nickel prices and project economics improve.
The regulatory warning makes that optionality less certain. Delays raise transaction costs, postpone integration and leave MMG exposed to changes in nickel prices while it waits for clearance. The company must also assess whether additional EU commitments would constrain marketing flexibility or reduce the value of the acquired production.
The stock-market angle is therefore less about a single antitrust headline and more about execution. For Anglo American shareholders, the question is whether the company can complete its portfolio simplification on acceptable terms. For MMG investors, the focus is whether the Brazilian assets can deliver diversification without adding disproportionate regulatory and commodity risk.
Neither case provides a straightforward trading signal. The outcome will depend on the final remedies, the timing of approval and the direction of the nickel market.

Nickel-bearing material moving through an industrial handling and loading system.
Nickel deal scenarios
| Scenario | Regulatory outcome | Market implication |
|---|---|---|
| Base case | MMG offers strengthened European supply commitments and receives conditional approval | Deal closes later and with tighter marketing obligations |
| Bull case for MMG | Regulators accept targeted remedies without structural changes | MMG gains Brazilian diversification and project optionality |
| Bear case for MMG | The Commission rejects revised remedies or prohibits the transaction | Anglo must seek another buyer or retain the assets; MMG loses the planned entry into Brazil |
The broader lesson for mining M&A deals in 2026 is that regulatory risk is expanding alongside the strategic value of critical minerals. A transaction can be commercially attractive and still face resistance if regulators believe it could affect regional access to a narrowly supplied industrial product.
For MMG and Anglo American, the next stage will be shaped by the Commission’s formal objections and the parties’ response. For the wider nickel industry, the case will show how European regulators intend to balance competition policy with the region’s growing concern over industrial supply security.
Shareable social snippets
LinkedIn:
MMG’s proposed $500 million acquisition of Anglo American’s Brazilian nickel assets faces a new EU antitrust hurdle. Regulators are examining whether the deal could affect ferronickel supply to European stainless-steel producers. The case highlights how competition reviews are increasingly intersecting with critical-minerals policy and supply-chain security.
X:
MMG’s $500m purchase of Anglo American’s Brazilian nickel assets faces an expected EU antitrust warning. Brussels is focused on ferronickel supply, European stainless steel and the implications of Chinese-controlled ownership. Read the analysis.