

Rare earth supply chain steps run from mined ore through crushing, chemical separation, oxide refining, metallisation, alloying, and finally sintered magnet manufacturing. Each stage is technically distinct, capital-intensive, and concentrated in ways that create strategic risk — and understanding the full sequence is essential to understanding why rebuilding this chain outside China is so difficult.
Why Do the Supply Chain Steps Matter More Than the Mine?
For years, policy debates about rare earths focused on who had the deposits. That framing missed the point.
Mining is only the first of six or seven distinct industrial stages. A country can have abundant reserves in the ground and still depend entirely on foreign infrastructure before those materials become a usable industrial input. China understood this decades ago. Most Western policymakers are only now catching up.
According to the International Energy Agency (IEA), China accounted for roughly 60% of global mined production of magnet rare earths in 2024 — but 91% of refined output and 94% of global sintered permanent magnet production. The gap between those numbers tells the real story.
Control of processing and magnet manufacturing gives a dominant producer leverage far beyond what its mining share alone would suggest.
What Are the Six Core Rare Earth Supply Chain Steps?
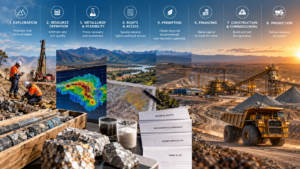
The rare earth supply chain is best understood as a sequential series of industrial processes. Moving from step to step requires different technology, different equipment, different skills, and different capital structures. Here is how each stage works.
More Read
Step 1: Mining and Ore Extraction
Rare earth elements do not occur in concentrated pockets.. They occur in low-grade ore bodies, often alongside other minerals and, in some deposits, radioactive thorium or uranium. The primary ore types include:
- Carbonatite deposits — such as Mountain Pass in California and Bayan Obo in Inner Mongolia, which contain bastnäsite, a carbonate-fluoride mineral
- Ion-adsorption clays — found in southern China, where rare earths are adsorbed onto clay particles at low concentrations
- Monazite and xenotime sands — heavy mineral sands found in Australia, India, and parts of Africa
Mining method depends on deposit type. Hard rock deposits require conventional open-pit or underground extraction. Ion-adsorption deposits can be leached in-situ, though this creates its own environmental challenges.
At this stage, the product is raw ore. It has no direct industrial application.
More Read
Step 2: Ore Processing and Concentration (Beneficiation)
Raw ore goes through a physical and chemical upgrading process to raise the concentration of rare earth minerals before chemical processing begins. This stage is called beneficiation.
Typical beneficiation steps include:
- Crushing and grinding the ore to liberate the target minerals from the surrounding rock
- Gravity separation, magnetic separation, or flotation to remove gangue (unwanted minerals)
- Acid leaching in some deposit types, particularly ion-adsorption clays, to dissolve rare earth ions into solution
- Thickening and filtration to produce a rare earth concentrate
The output of beneficiation is a mixed rare earth concentrate — a higher-grade material that still contains all the individual rare earth elements together. It has not yet been separated into its components.
This stage generates significant waste material, known as tailings, which must be managed carefully. The scale of tailings at major facilities — such as the Baotou tailings lake in Inner Mongolia — illustrates why environmental management is a genuine technical and regulatory challenge, not merely a political talking point.
Step 3: Chemical Upgrading and Separation
This is the most technically demanding stage in the rare earth supply chain, and the step where China’s dominance is most structurally entrenched.
Rare earth elements are chemically very similar to one another. Separating them into individual pure oxides requires sophisticated liquid-liquid solvent extraction — a process that uses organic solvents and aqueous acid solutions in a long series of stages (sometimes hundreds of sequential mixer-settler units) to exploit tiny differences in chemical behaviour between the elements.
The separation process involves:
- Dissolving the concentrate in acid to produce a rare earth solution
- Running the solution through a cascade of solvent extraction stages, each one selectively moving specific elements between an organic and aqueous phase
- Stripping and re-extracting individual elements to achieve the required purity levels
- Precipitating individual rare earth compounds (typically as oxalates or carbonates) and calcining them to produce oxides
The output is a set of separated rare earth oxides — individual products such as neodymium oxide, praseodymium oxide, dysprosium oxide, terbium oxide, lanthanum oxide, and cerium oxide, each at defined purity levels.
Building separation capacity from scratch requires large-scale lined tankage, specialist analytical equipment such as ICP-MS instruments for quality control, deep process chemistry expertise, robust waste treatment systems for acid and solvent streams, and long operating timelines before a facility reaches stable output. This is precisely why refining capacity lags so far behind mining capacity in announced non-Chinese projects.
Step 4: Metal Refining (Reduction to Metal)
Separated rare earth oxides are not yet in a form that magnet manufacturers can use. They must first be converted into metals.
This step — sometimes called metallisation — involves reducing the oxide to a pure metal. For neodymium and praseodymium, the dominant process is molten salt electrolysis, in which the oxide is dissolved in a fluoride salt bath and metallic rare earth is deposited at a cathode under electrical current.
For some heavy rare earths such as dysprosium and terbium, metallothermic reduction (using calcium as a reducing agent) is also used.
The output at this stage includes:
- Neodymium metal and didymium metal (a neodymium-praseodymium alloy used directly in magnet production)
- Dysprosium metal
- Terbium metal
- Other individual rare earth metals as required
The IEA identifies metallisation as one of the most acute constraints on supply chain diversification outside China. A country can have working separation facilities and still be unable to supply magnet-grade metal without this capability in place.
Step 5: Alloying
Rare earth metals are combined with iron and boron — and sometimes other additives — to produce the alloy that forms the basis of a neodymium-iron-boron (NdFeB) permanent magnet.
This alloying step is typically done by melting the constituent metals together in a vacuum or inert atmosphere furnace and casting the melt into an alloy. The alloy can then be processed into various intermediate forms, including:
- Strip-cast alloy — a thin ribbon of alloy solidified rapidly on a water-cooled wheel, which gives a fine microstructure suited to magnet production
- Hydrogenation, Disproportionation, Desorption and Recombination (HDDR) processed alloy — used for bonded magnets
The composition of the alloy determines the intrinsic magnetic properties of the final product. Heavy rare earths such as dysprosium and terbium are sometimes added at this stage or applied later via grain-boundary diffusion to improve coercivity — the magnet’s resistance to demagnetisation at high temperatures.
Step 6: Magnet Manufacturing
The final stage converts rare earth alloy into finished permanent magnets. For sintered NdFeB magnets — the type used in electric vehicle motors, wind turbines, and defence systems — the process involves:
- Milling the alloy into fine powder, typically using hydrogen decrepitation and jet milling
- Aligning the powder particles in a magnetic field to orient the crystallographic structure
- Pressing the aligned powder into a green compact
- Sintering the compact in a vacuum furnace at high temperature to fuse the particles into a dense, solid magnet
- Heat treatment to optimise coercivity
- Machining and coating the magnet to final dimensions and applying a protective surface finish
China’s share of global sintered NdFeB magnet production grew from approximately 50% in 2005 to 94% in 2024, according to IEA data. That concentration reflects not just technical capability but economies of scale, established supply networks, specialist workforce depth, and customer relationships built over decades.
New producers outside China are not just building factories. They are building an entire industrial ecosystem.
What Does the Processing Gap Look Like in Numbers?
The IEA’s projections for capacity outside the leading supplier by 2035 illustrate the structural imbalance across the supply chain steps:
| Supply Chain Stage | Planned Capacity Outside China (by 2035) |
|---|---|
| Mining | >50,000 tonnes |
| Refining and Separation | <40,000 tonnes |
| Metals, Alloys, and Magnets | ~18,000 tonnes (rare earth content basis) |
Each step downstream, available capacity shrinks. Projects that address mining without building matching downstream infrastructure simply shift the dependency rather than eliminating it.
Why Is Rebuilding Each Step So Difficult?
The challenges vary by stage, but several factors run across the entire chain:
Technical know-how — Separation chemistry, metallisation processes, and magnet sintering all require deep operational experience that has not existed at scale outside China for decades. The knowledge base atrophied when Western capacity was transferred or closed.
Permitting and waste management — Acid and solvent waste from separation, radioactive material management in some ore types, and tailings from beneficiation all require extensive regulatory compliance. This adds years to project timelines in Western jurisdictions.
Capital intensity and project timelines — A scoping study is not a bankable number. Progressing from early study through bench-scale testwork, pilot operation, pre-feasibility study, definitive feasibility study, and final investment decision typically takes many years per gate. Capital costs for critical mineral refining outside dominant suppliers are estimated by the IEA at 20% to more than 150% higher than equivalent Chinese capacity.
Equipment procurement — Specialist lined vessels for solvent extraction, analytical instruments, and other processing equipment face long lead times and a limited number of qualified suppliers outside China.
Financing — Without long-term offtake agreements or government-backed floor prices, projects struggle to attract commercial finance. The Molycorp experience at Mountain Pass demonstrated that price cycles can destroy project economics even after significant capital has been deployed.
Can Government Support Make Non-Chinese Supply Chains Viable?
Government contracts, price floors, and long-term offtake agreements are already part of the landscape in the United States and Australia. But structure matters as much as scale.
A contract that locks in volume but provides no price floor does not protect a producer against commodity price falls. Arrangements that include minimum floor pricing or contract-for-difference structures provide more durable support for project financing.
Even with government support, the IEA estimates that announced projects outside the dominant supplier would cover only about half of projected mining demand, roughly one-quarter of refining demand, and well below 20% of magnet demand by 2035.
The shortfall is largest at the downstream steps — exactly where the strategic leverage of rare earth processing is highest.
What Role Can Recycling Play?
Recycling does not eliminate the need for primary supply, but it can reduce pressure on each step of the chain.
The IEA estimates that recycling could reduce demand for primary rare earth supply by up to 35% by 2050. Current recycling is dominated by manufacturing scrap — offcuts and process losses from magnet production. Future growth in electric vehicles, wind turbines, and consumer electronics will create larger volumes of end-of-life material.
For countries building domestic supply chains, recovering rare earths from end-of-life magnets offers both a secondary source of refined material and a way to reduce the volume of ore that needs to pass through every upstream step.
Key Takeaways: Rare Earth Supply Chain Steps at a Glance
- Step 1 — Mining: Ore is extracted. The product is raw rock with low rare earth content.
- Step 2 — Beneficiation: Ore is crushed, sorted, and chemically upgraded to produce a mixed rare earth concentrate.
- Step 3 — Separation: Solvent extraction separates the mixed concentrate into individual rare earth oxides. This is the most technically demanding and strategically critical step.
- Step 4 — Metal Refining: Individual oxides are reduced to metals through electrolysis or metallothermic processes.
- Step 5 — Alloying: Rare earth metals are combined with iron and boron to produce NdFeB alloy.
- Step 6 — Magnet Manufacturing: Alloy is milled, pressed, sintered, and finished into permanent magnets.
Each step is a distinct industrial capability. Having ore in the ground does not guarantee access to finished magnets. The rare earth race has moved from the mine to the factory — and the outcome will depend on how successfully new projects connect every stage of this chain.