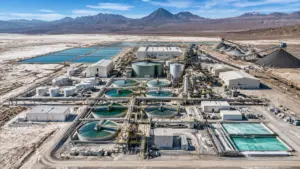
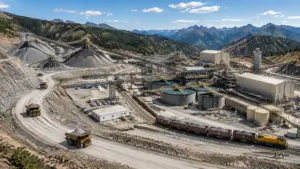
Drilling at the Boumadine project in Morocco’s Anti-Atlas region.

Aya Gold & Silver has more than doubled the after-tax net present value of its Boumadine project in Morocco to US$3.5 billion, or approximately C$4.8 billion, while extending the planned mine life and increasing expected silver production.
The updated preliminary economic assessment, reported by The Northern Miner, gives Boumadine an after-tax NPV at a 5% discount rate of US$3.537 billion, compared with US$1.475 billion in the previous study. Aya said the updated project also carries a 93% after-tax internal rate of return and a payback period of just 0.7 years from first production.
The figures strengthen Boumadine’s position as one of the most important undeveloped precious-metals projects in Morocco. They also put renewed attention on the country’s Anti-Atlas mining belt, where Aya already operates the Zgounder silver mine.
Yet the headline valuation requires context. The numbers come from a preliminary economic assessment, not a completed feasibility study, and the model includes inferred mineral resources that do not yet have demonstrated economic viability.
Higher prices, more metal and a longer mine life
Aya’s updated study is based on a price deck of US$3,500 per ounce for gold, US$50 per ounce for silver, US$1.37 per pound for zinc and US$0.90 per pound for lead.

The gold and silver assumptions are significantly higher than those used in the previous assessment. The 2025 study used US$2,800 gold and US$30 silver. The updated price assumptions therefore account for a substantial part of the change in project value.
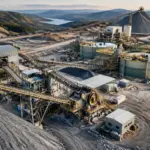
Boumadine’s planned mine life has also increased from 11 years to approximately 14 years. The mine plan includes multiple open pits and underground operations feeding a conventional flotation plant with capacity of 8,000 tonnes per day, or approximately 2.9 million tonnes annually.
Initial capital expenditure is estimated at US$463 million, only modestly above the previous estimate of US$446 million. That combination : materially higher projected value without a comparable increase in initial capital : lifts Aya’s stated NPV-to-capex ratio to 7.6 times, from 3.3 times in the prior study.
| Boumadine project metric | Updated PEA | Previous PEA | Change |
|---|---|---|---|
| After-tax NPV at 5% | US$3.537B | US$1.475B | +140% |
| After-tax IRR | 93% | 47% | +46 percentage points |
| Payback period | 0.7 years | 2.1 years | -1.4 years |
| Initial capital | US$463M | US$446M | +4% |
| Mine life | 14 years | 11 years | +3 years |
| Life-of-mine silver production | 81.2 Moz | 69.9 Moz | +16% |
| Life-of-mine gold-equivalent production | 3.9 Moz | 3.6 Moz | +7% |
Source: Aya Gold & Silver’s updated Boumadine PEA.
Morocco’s emerging silver and polymetallic district
Boumadine is located in Morocco’s Errachidia province, approximately 220 kilometres east of Ouarzazate and 70 kilometres southwest of Errachidia. The project sits within the Anti-Atlas, a mineral-rich geological belt that hosts several historic and modern mining operations.
Aya controls a land package of roughly 340 square kilometres at Boumadine, alongside an additional exploration authorization covering about 600 square kilometres. The current resource estimate and mine plan cover only part of that broader exploration footprint.
The project is not a conventional silver-only mine. It is a polymetallic operation containing gold, silver, zinc and lead. Aya’s planned processing facility would produce separate zinc, lead and pyrite concentrates, with gold and silver credits providing much of the project’s economic value.
According to Aya’s project information, revenue in the updated study is driven primarily by gold and silver, with zinc and lead contributing additional by-product value. The project is expected to produce approximately:
- 2.25 million ounces of gold
- 81.2 million ounces of silver
- 422,000 tonnes of zinc
- 195,000 tonnes of lead
over the life of the mine.
The planned first-five-year production profile averages approximately 348,000 ounces of gold equivalent annually, before declining to a life-of-mine average of 271,000 ounces.

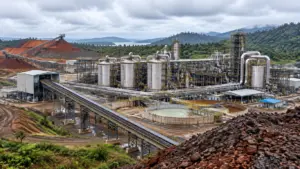
Boumadine’s remote Anti-Atlas setting highlights the infrastructure required to advance a district-scale project.
Aya’s existing Zgounder operation gives the company a producing base in Morocco and local operating experience. The company has said Boumadine could eventually double its silver production, although the development-stage project remains subject to further technical work, financing and approvals.
What drove the valuation increase?
The updated NPV is not the result of a single geological breakthrough. It reflects several changes made between the two assessments.
First, the price assumptions are more favorable. The assumed silver price rises by 67%, from US$30 to US$50 per ounce, while the gold assumption increases by 25%. Those changes are particularly important for a project where precious metals account for most projected revenue.
Second, Aya has increased expected metal payability. Average payability rises to approximately 83% on a gold-equivalent basis from 73% in the previous study. Payability represents the portion of contained metal that can ultimately be credited in concentrate sales after treatment, refining and other commercial deductions.
Third, the mine plan processes more material over a longer operating period. Life-of-mine processed tonnes increase to approximately 41.2 million from 31.1 million, while silver production rises by 16%.
Finally, the resource base has expanded. The updated mineral resource estimate includes 8.6 million tonnes of indicated resources containing 1.1 million ounces of gold equivalent, and 45.4 million tonnes of inferred resources containing 4.3 million ounces of gold equivalent.
The company is conducting an additional drilling campaign of up to 400,000 metres, with most of the work focused on resource definition and conversion. A feasibility study is targeted for completion and disclosure in the second half of 2027.
The silver price prediction 2026 question
For investors assessing a silver price prediction for 2026, Boumadine offers a useful example of how commodity assumptions can influence a mining project’s valuation.
Aya’s sensitivity analysis estimates an after-tax NPV of approximately US$1.8 billion under a lower-price case using US$2,625 gold and US$37.50 silver. Under the base case, NPV rises to US$3.537 billion. Using the company’s cited spot-price case of US$4,472 gold and US$66.85 silver, NPV reaches approximately US$5.5 billion.
| Scenario | Gold price | Silver price | After-tax NPV | After-tax IRR |
|---|---|---|---|---|
| Bear or lower-price case | US$2,625/oz | US$37.50/oz | US$1.808B | 57% |
| Base case | US$3,500/oz | US$50.00/oz | US$3.537B | 93% |
| Bull or cited spot-price case | US$4,472/oz | US$66.85/oz | US$5.525B | 128% |
The scenarios are sensitivities to the financial model rather than forecasts. Aya cautions that mine design, cut-off grades and processing schedules would likely change under different commodity-price environments.
That distinction matters. A strong silver market can improve revenue, margins and project financeability, but it can also raise costs for equipment, construction, energy and labor. In addition, Boumadine’s value is linked to gold as much as silver, with zinc and lead adding further exposure to base-metal markets.
The company and stock-market angle
In plain market terms, the Boumadine update gives Aya a powerful growth narrative: a producing silver mine in Morocco, a large development asset, rising resource confidence and a projected capital requirement that remains relatively small compared with the updated project value.
That is the part of the story that would attract a high-energy market commentator: the company has reported a large increase in value while keeping initial capital broadly stable. Aya also says it intends to fund Boumadine through existing cash flow and external debt, limiting the need for equity dilution if those plans remain achievable.
But the less promotional interpretation is equally important. The US$3.5 billion figure is a project-level PEA value, not Aya’s market capitalization and not a guaranteed acquisition price. It also does not account for the discount that public markets typically apply to development-stage assets, construction risk, financing requirements, country exposure and the time required to reach production.
The next milestones are therefore more important than the headline NPV alone. Investors will be watching for resource conversion, the feasibility study, environmental and social assessment work, infrastructure costs, concentrate offtake terms and the final financing structure.
For readers tracking mining M&A deals in 2026, Boumadine illustrates why large, high-margin development assets are likely to remain strategically relevant. A project with a projected 7.6-times NPV-to-capex ratio and substantial precious-metals exposure could attract attention from larger producers seeking growth. However, any transaction would need to reflect the project’s PEA status, construction risk and the possibility that the economics change as the study advances.

The planned Boumadine operation would use conventional flotation to produce zinc, lead and pyrite concentrates.
What comes next
Aya’s immediate task is to convert a compelling preliminary model into a financeable development plan.
The company must define reserves, complete engineering, validate infrastructure and logistics assumptions, and demonstrate that the planned flotation process can deliver the expected recoveries and concentrate quality at commercial scale. Boumadine will also require a 72-kilometre power line, water infrastructure, tailings capacity and a long-distance transport route to Morocco’s Nador-West port.
The project’s exploration upside is significant, but it cuts both ways. Additional drilling could support a larger operation or longer mine life. It could also increase the capital required and complicate the development schedule.
Boumadine has therefore moved from an exploration story toward a project-execution story. Its updated economics are substantial, and Morocco’s established silver-mining base gives Aya a valuable operating context. The central question now is whether the company can preserve those economics as the project moves from PEA-level assumptions to feasibility-stage engineering, permitting and financing.
For additional project details, see Aya’s Boumadine project page. For broader context on project valuation and sector consolidation, see Skillings’ analysis of project P/NAV valuation and mining M&A deals in 2026.
The Boumadine PEA is preliminary in nature and includes inferred mineral resources. Mineral resources are not mineral reserves and do not have demonstrated economic viability. Actual results may differ materially from the estimates and assumptions presented by Aya Gold & Silver.