A big resource does not make a mine. Neither does a promising feasibility study.

Before North Stanmore can get anywhere near production, Victory Metals needs the right to develop the ground. It now has that tenure.
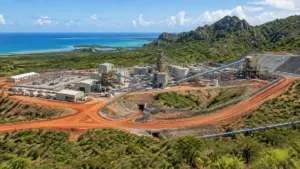
Victory Metals has secured Mining Lease M20/564 covering about 2,006 hectares at its North Stanmore Heavy Rare Earth Project near Cue in Western Australia. Western Australian authorities granted the lease on 11 September 2026, converting six exploration licences into full mining tenure and partially converting four others.
For a rare earth project still moving through development, that changes the nature of the risk.
Why the mining lease matters
An exploration licence gives a company the right to explore. A mining lease gives it a much stronger legal position to develop a mineral deposit, subject to the approvals that still lie ahead.
More Read
That distinction matters for a project seeking serious capital.

Victory has already completed several major pieces of technical work at North Stanmore. In August, the company released a maiden Ore Reserve, an updated Mineral Resource Estimate and a Pre-Feasibility Study. It has also commissioned a pilot plant in Perth that has produced rare earth mineral concentrate.
The mining lease removes one layer of uncertainty from that development story. Lenders, strategic investors and potential offtake partners can now assess the project with greater certainty around its tenure.
But the lease does not give Victory a production permit. Environmental approvals, detailed engineering, financing, offtake agreements and a final development decision still matter.
North Stanmore’s heavy rare earth advantage
North Stanmore stands out because of its heavy rare earth element content.
Heavy rare earths such as dysprosium and terbium play an important role in high-performance permanent magnets. Manufacturers use these magnets in applications where strength and performance at higher temperatures matter, including electric motors, advanced electronics and defence technologies.
The supply chain for several of these materials remains highly concentrated. That gives projects outside China strategic relevance, particularly when governments and manufacturers look for alternative sources of critical minerals.
Victory is positioning North Stanmore around that opportunity. The company has also reported gallium at the project, adding another critical-mineral angle to the broader resource.
The project already has a development case
The mining lease arrives after Victory published its August PFS.
The study outlined a 20-year development case, including a proposed 2.4-million-tonne-per-year flotation operation. Victory reported initial capital expenditure of about A$155 million and a post-tax NPV8 of A$1.21 billion.
The company also reported a maiden Probable Ore Reserve of 47 million tonnes grading 692 parts per million total rare earth oxide.
Those numbers give investors something more concrete than an exploration story to assess. They also come with an important qualification: a PFS remains a study, not a final investment decision. Actual project costs, construction requirements, financing terms and operating performance can change as development moves forward.
Financing is the next big test
Victory has already opened discussions with potential funding partners.
In 2025, the company secured an indicative letter of interest from the US Export-Import Bank for potential financing of up to US$190 million. The proposal remains non-binding and depends on due diligence, policy requirements and final approval.
That difference is important. An LOI is not approved project finance, and it is not financial close.
The mining lease strengthens Victory’s position as it takes those discussions further. The company can now point to a more advanced project with established tenure, a completed PFS, an Ore Reserve and pilot-scale processing work.
The next announcements will tell investors much more: who is prepared to finance North Stanmore, who is willing to buy its concentrate, and whether the proposed processing route continues to perform as development advances.
From tenure risk to execution risk
The North Stanmore story has moved beyond the question of whether Victory can secure the ground it needs.
The company now faces a different set of challenges.
Financing must come together. Offtake agreements must move from discussions to firm commitments. Technical and environmental work must continue. The proposed mine and processing operation must also deliver against the assumptions in the PFS.
For Victory Metals, the mining lease is therefore an important milestone, but not the finish line.
North Stanmore now has the tenure. The harder question is whether Victory can turn that tenure, its rare earth resource and its development studies into a financed and commercially viable mine.