Copper busbars used in power infrastructure.

By Penny Langford
Copper’s move toward $14,000 per tonne is testing whether supply relief expected in 2026 can keep pace with demand from grids, data centers, electric vehicles and broader electrification.
The market has already shown how quickly conditions can change. Copper briefly surpassed $14,500/t in January, according to J.P. Morgan Global Research, while Skillings reporting placed the metal near $14,285/t in early September. The rally has been supported by mine disruptions, tariff positioning, regional inventory imbalances and constrained concentrate availability.
The key question for operators and investors is whether new deliveries and recovering mines will create meaningful relief: or merely slow the pace of tightening.
Copper price forecast 2026: the market is tight, but forecasts diverge
Institutional forecasts remain widely spread.

The World Bank and several bank and consultancy estimates place the 2026 average broadly in the low-$12,000s per tonne. A Reuters analyst poll cited a median forecast of $11,975/t for the year, while S&P Global Market Intelligence expects an average slightly above $12,100/t.
J.P. Morgan’s quarterly path is more constructive, with forecasts of $13,500/t in the second quarter, $13,000/t in the third quarter and $12,500/t in the fourth quarter. By contrast, Goldman Sachs Research expects supply growth and demand sensitivity to keep copper in a lower range for much of 2026.
The divergence reflects a market caught between two forces:
- Structural demand growth from power infrastructure, AI-related data centers and energy-transition projects.
- Cyclical and supply-side relief from mine recoveries, project ramp-ups, scrap and demand rationing at elevated prices.
As a result, $14,000/t is best viewed as an upside test rather than a settled base case.
New mine deliveries may provide relief: but not a surplus everywhere
The 2026 supply response is expected to come from three sources: the recovery of disrupted mines, incremental production from expansions and new deliveries, and higher refined output from smelters and secondary material.
Forecasts differ on the scale of that response. BMI, cited by Mining Weekly, expects global mine production to rise by approximately 3.3% year over year in 2026. The increase is linked partly to the recovery of major operations disrupted in 2025, including Grasberg in Indonesia, El Teniente in Chile and Kamoa-Kakula in the Democratic Republic of Congo.
The International Copper Study Group, as summarized by Mitrade, has published a more cautious supply picture, with mine production growth of around 1.6% and refined production growth of only 0.4%. Refined usage, by comparison, is expected to grow by approximately 1.6%.
That distinction matters. A recovery in mine production does not immediately translate into abundant cathode. Concentrate must still be transported, processed and refined. Smelter constraints, maintenance schedules, sulfuric acid availability and regional logistics can delay the arrival of new material to consumers.

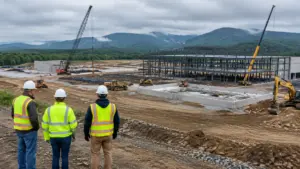
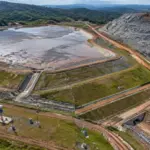
Open-pit mining infrastructure highlights the scale and complexity of primary copper supply.
A linkable 2026 copper supply and demand framework
The following table summarizes the main supply and demand indicators shaping the 2026 outlook.
| Indicator | 2026 reference | Why it matters |
|---|---|---|
| Global mine production growth | 1.6%–3.3% | Recovery at disrupted mines may add units, but forecasts vary significantly |
| Refined production growth | 0.4%–1.1% | Indicates that mine relief may not immediately become cathode relief |
| Refined usage growth | Around 1.6% | Demand may continue to outpace refined supply in tighter forecasts |
| Goldman Sachs market balance | Surplus in the range of 160,000–300,000 tonnes, depending on estimate | Scrap, demand rationing and mine recovery could cap prices |
| J.P. Morgan Q2 price forecast | $13,500/t | Shows how high prices could remain even under a more cautious macro view |
| J.P. Morgan Q4 price forecast | $12,500/t | Reflects expected easing if inventories and supply improve |
| Bull-case market test | $14,000–$15,000/t | Requires supply disappointments, low inventories and resilient demand |
Sources: J.P. Morgan Global Research, Goldman Sachs Research, Mining Weekly, Mitrade and S&P Global Market Intelligence.
The table shows why the supply outlook is not simply bullish or bearish. Mine output may recover, but refined production could remain constrained. At the same time, higher prices may increase scrap supply and encourage aluminum substitution, placing a ceiling on demand.
Why concentrate availability remains important
Treatment and refining charges are among the clearest indicators of pressure in the copper supply chain.
When charges fall toward zero, smelters are competing aggressively for concentrate. That generally means mining supply is not keeping pace with available refining capacity. The result can be a market where refined copper appears available in some regions while raw material remains scarce for processors.
This distinction is central to the copper price forecast 2026. New mine deliveries may improve the concentrate balance without creating an immediate surplus of refined copper. Any delays at major mines, transport bottlenecks or processing interruptions could therefore keep prices elevated.
The International Energy Agency has warned that copper supply chains face growing strategic pressure as electrification accelerates and smelters contend with limited feedstock.
For producers, low treatment charges can support concentrate pricing but also expose the market to operational disruptions. For smelters, the same conditions can compress margins and increase competition for long-term supply contracts.
Demand is expanding, but $14,000 changes consumer behavior
The long-term demand case remains linked to electricity.
Transmission lines, substations, transformers, renewable power systems, electric vehicles and charging networks all require copper. Data centers add demand through power distribution, cooling systems and backup infrastructure.
Goldman Sachs Research estimates that grid and power infrastructure could account for more than 60% of copper demand growth through 2030. The firm also expects AI and defense investment to increase demand for resilient power networks.
But prices near $14,000/t create resistance. Fabricators can increase scrap use, reduce copper intensity, substitute aluminum in selected applications or delay projects that are not immediately essential. These responses are gradual, but they become more powerful the longer elevated prices persist.
High copper prices therefore have a dual effect: they improve revenue potential for producers while encouraging consumers to find alternatives. The resulting demand response may be enough to prevent a shortage from becoming a sustained deficit.

Copper cathode availability depends on both mine supply and refining capacity.
Copper price scenarios for 2026
These scenarios are analytical ranges, not investment recommendations.
| Scenario | Indicative 2026 price path | Core assumptions | Operational implication |
|---|---|---|---|
| Base case | $11,800–$13,000/t average | Mine recoveries proceed, refined supply improves gradually, demand remains firm but price-sensitive | Producers benefit from strong prices, but cost inflation and project execution remain important |
| Bull case | $14,000–$15,000/t test | New supply underperforms, inventories remain geographically concentrated, grid and AI demand stays resilient | Operators may accelerate expansions, while consumers increase substitution and inventory discipline |
| Bear case | $10,500–$11,500/t | Mine recoveries succeed, scrap rises, Chinese demand weakens and macroeconomic conditions deteriorate | Higher-cost projects face pressure; fabricators and smelters gain purchasing flexibility |
Base case: supply relief limits the upside
The base case assumes that 2026 deliveries and mine recoveries arrive, but not quickly enough to create a deep surplus.
Grasberg, El Teniente and Kamoa-Kakula contribute more material, while higher prices draw additional scrap into the market. Demand from power infrastructure remains supportive, but high borrowing costs and weak property activity limit consumption elsewhere.
Under this outcome, copper can remain above historical averages while easing from the most elevated levels. A sustained average in the low-$12,000s would be consistent with a market that is better supplied but not comfortable.
Bull case: $14,000 becomes a sustained test
The bull case requires supply relief to disappoint.
Delays at recovering mines, further disruptions in Chile or Indonesia, and continued pressure in the concentrate market would leave refined copper vulnerable to another price surge. The upside would be stronger if inventories remained concentrated in the United States or other locations unable to serve immediate demand elsewhere.
The bull case also requires demand to remain resilient despite high prices. Grid investment, data-center construction and strategic infrastructure spending would need to offset weaker traditional industrial activity.
Bear case: new deliveries meet slower demand
The bear case develops if supply arrives as planned while demand slows.
A successful recovery at disrupted mines, stronger refined production and increased scrap flows could move the market toward surplus. If Chinese consumption weakens further, the effect would be amplified.
J.P. Morgan identifies a potential support zone around $11,100–$11,200/t under a more adverse macroeconomic scenario. Goldman Sachs has also argued that high prices could encourage demand destruction and additional secondary supply.
A move toward the low-$11,000s would not invalidate the long-term electrification theme. It would indicate that the market is responding to price by bringing forward supply and reducing consumption.
Operational implications for mining companies and buyers
Mining companies should focus on whether elevated prices are durable enough to justify higher-cost expansions, debottlenecking and mine-life extensions. The central risk is committing capital on the assumption that a temporary policy or inventory distortion represents a structural shortage.
Smelters should monitor treatment charges, sulfuric acid availability and concentrate contract terms. Near-zero charges can signal strong refined-market pricing, but they also indicate vulnerability to feedstock disruptions.
Fabricators and industrial buyers should track regional premiums, warehouse cancellations and cash-to-three-month spreads. These indicators can reveal whether copper is genuinely scarce or simply concentrated in the wrong location.
Investors and policymakers should also distinguish between mine production growth and refined supply growth. A headline increase in mining output may not translate into immediate relief for manufacturers.
The practical conclusion is balanced. The copper price forecast 2026 supports a market that remains historically expensive, but the path toward $14,000/t depends on whether new deliveries arrive on schedule and whether demand remains resilient at elevated prices.
The base case points to gradual easing from the highs. The bull case remains credible if mine recoveries disappoint and concentrate remains scarce. The bear case becomes more likely if new supply, scrap and weaker demand arrive together.
Copper’s next phase will be determined not only by how much metal is produced, but by where it is available, how quickly it can be refined and whether consumers can continue paying for it.
For related analysis, read Skillings’ coverage of the copper market squeeze, the copper demand outlook from AI and grid investment and critical-minerals supply-chain concentration.
This article is for information and market analysis only. It does not constitute financial advice or a recommendation to buy or sell any security.
Social snippets
Copper near $14,000/t is facing a critical test in 2026. Recoveries at major mines could bring supply relief, but refined output may still lag demand from grids, AI data centers and electrification. Our base, bull and bear framework examines what could push copper toward $15,000: or back toward the low-$11,000s.
X
Copper’s $14,000 test depends on whether new mine deliveries become real refined supply. Mine recoveries may add units in 2026, but concentrate constraints, grid demand and AI infrastructure could keep the market tight. Full copper price forecast 2026 analysis: base, bull and bear cases.