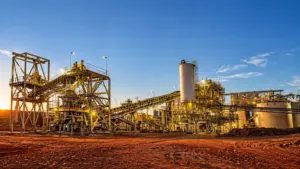
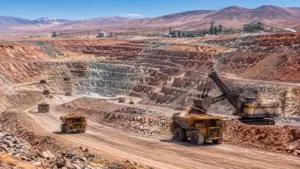
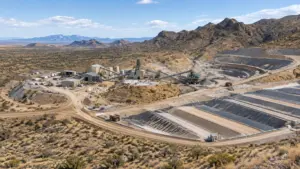
Brazilian ferronickel processing infrastructure at an industrial nickel operation.

China-backed MMG has offered long-term ferronickel supply guarantees to European customers in an effort to secure regulatory approval for its proposed US$500 million purchase of Anglo American’s Brazilian nickel business.
The offer follows a formal Statement of Objections issued by the European Commission on Sept. 16. The Commission warned that the transaction could weaken competition in the European ferronickel market, potentially allowing prices to rise for stainless steel producers that rely on the material.
MMG is now seeking to address those concerns without giving up control of the Brazilian assets. The European Commission’s final decision is due by Nov. 30, 2026, leaving the parties with a limited window to negotiate, formalize and defend the proposed remedies.
The case puts a critical minerals supply-chain issue at the center of a major mining transaction: whether long-term commercial commitments can provide European buyers with sufficient protection after a change in ownership.
MMG’s remedy offer targets European supply
MMG has told European regulators and customers that it is prepared to maintain, or potentially increase, ferronickel and nickel supplies to Europe over the long term.

The company’s executive general manager for corporate relations said MMG was willing to commit to arrangements that would leave European customers “in as good or a better place than they were with Anglo.”
The proposed guarantees are expected to focus on direct supply commitments to European buyers. That approach would differ from an earlier remedy associated with Anglo American, under which Anglo would have purchased ferronickel from MMG and resold it into Europe for up to 10 years.
That earlier proposal did not resolve the Commission’s concerns, according to reporting on the case. Regulators questioned whether the arrangement provided sufficient certainty over volumes, pricing and access to supply.
MMG’s new offer appears designed to address those concerns more directly by placing the commitments with the post-transaction owner rather than relying on an intermediary resale structure.
However, the details of the proposed guarantees have not been fully disclosed. The Commission will need to assess the duration of the contracts, minimum volumes, pricing terms, eligible customers, enforcement mechanisms and the consequences if MMG fails to deliver.

Ferronickel processing depends on large-scale furnace and metal-handling systems.
Why the EU is concerned about the deal
MMG agreed in February 2025 to acquire Anglo American’s Brazilian nickel business for up to US$500 million. The consideration consists of US$350 million in upfront cash and up to US$150 million in contingent payments linked to nickel prices and future development decisions.
The assets include the Barro Alto and Codemin operations in Brazil. Together, they produce approximately 40,000 tonnes of nickel in ferronickel each year, according to MMG’s transaction announcement.
Ferronickel is primarily used in stainless steel. MMG says roughly two-thirds of refined nickel production is consumed by the stainless steel industry, where nickel typically represents between 8% and 10% of the finished alloy.
The Commission’s concern is that MMG could redirect Brazilian ferronickel away from European customers after completing the acquisition. Regulators are examining whether the company could favor affiliated stainless steel producers or other buyers linked to its broader ownership structure, reducing supply available to European manufacturers.
The issue is particularly sensitive because European stainless steel producers have limited alternatives that can replace ferronickel quickly and at comparable cost. A reduction in available supply could increase the bargaining power of remaining suppliers and expose buyers to higher prices or less favorable contract terms.
The Commission’s objections are preliminary and do not represent a final finding that the transaction will be prohibited. MMG and Anglo American will have an opportunity to respond and submit commitments before the Commission reaches its decision.
MMG-Anglo nickel transaction: key numbers
| Item | Detail |
|---|---|
| Proposed buyer | MMG Ltd. |
| Seller | Anglo American plc |
| Transaction value | Up to US$500 million |
| Upfront consideration | US$350 million |
| Contingent consideration | Up to US$150 million |
| Brazilian assets | Barro Alto and Codemin |
| Approximate production | 40,000 tonnes of nickel in ferronickel per year |
| EU regulatory milestone | Statement of Objections issued Sept. 16, 2026 |
| Expected final decision | Nov. 30, 2026 |
Behavioural remedy faces an enforcement test
The central question for the Commission is whether a supply guarantee can deliver the same protection as continued ownership by Anglo American or another independent supplier.
Long-term supply commitments are known as behavioural remedies because they regulate how a company operates after a transaction. They do not change the ownership structure or remove assets from the deal.
Such remedies can be less disruptive than a divestment, but they are also harder to monitor. A commitment to supply a minimum volume may not protect customers if product quality changes, prices are reset through complex formulas or deliveries are delayed.
For the offer to gain traction, European buyers and regulators are likely to examine several practical issues:
- Volume: whether MMG guarantees the same quantity currently supplied by the Brazilian operations, and whether that volume can rise if European demand increases.
- Duration: whether commitments extend for enough years to support investment and procurement planning by stainless steel producers.
- Pricing: whether contracts provide transparent formulas and protection against excessive price increases.
- Customer access: whether existing buyers and new European entrants can participate on comparable terms.
- Monitoring: whether an independent trustee or regulator can verify compliance.
- Default provisions: whether customers receive meaningful protection if MMG misses deliveries or changes operating plans.
The Commission has historically shown a preference for structural remedies in cases where ownership concentration is the main concern. That may make the negotiating process more difficult, although the strategic importance of nickel supply could increase the value of a workable commercial solution.
The clock is now running to Nov. 30
The Statement of Objections moves the transaction into a more consequential phase. MMG must now respond to the Commission’s concerns while demonstrating that its proposed commitments are specific enough to be enforceable.
The timing also creates pressure for Anglo American. The company agreed to sell the Brazilian nickel business while reshaping its portfolio around copper, premium iron ore and crop nutrients. A prolonged regulatory review could delay proceeds, planning and management attention associated with the divestment.
For MMG, the transaction would establish its first operating presence in Brazil and add a primary nickel business to a portfolio that already includes copper, zinc and cobalt assets. The company has described the Brazilian operations as low-cost and supported by electricity sourced from renewable energy.
The deal would also add exposure to future development options, including the Jacaré and Morro Sem Boné projects, which could provide access to Class 1 battery-grade nickel if developed.
But the regulatory case has shifted the focus away from those growth options. The immediate issue is whether MMG can guarantee that European stainless steel producers will not be disadvantaged by the change in ownership.

Stainless steel producers are the principal downstream buyers of refined nickel.
Implications for the nickel market
The dispute comes as the nickel market continues to adjust to rapidly expanding supply, particularly from Indonesia, and weak pricing conditions across parts of the industry.
That broader surplus does not necessarily eliminate the Commission’s concern. Market-wide production may be high while specific forms of nickel, locations and customer relationships remain difficult to replace.
Ferronickel is especially relevant to stainless steel mills because it can be used directly in the production process. A European buyer cannot necessarily substitute another nickel product without changing its procurement, processing or quality-control arrangements.
The case also illustrates how competition regulators are applying supply-chain considerations to mining M&A. Traditional merger reviews often focus on market share, pricing power and the number of competitors. In critical minerals, regulators are increasingly examining ownership links, trade flows, processing capacity and the resilience of downstream industries.
That dynamic is visible across the wider sector. Skillings’ coverage of critical minerals supply chains has highlighted how processing concentration can create vulnerabilities even when mine supply appears adequate.
For nickel producers and buyers, the MMG case may establish a useful precedent. If long-term supply guarantees are accepted, future mining transactions involving strategically important materials could rely more heavily on customer-protection commitments. If the Commission rejects the offer, parties to similar deals may face greater pressure to sell or separate assets before seeking clearance.
What to watch next
The most important developments before the Nov. 30 deadline will be the publication of the remedy terms and the Commission’s assessment of whether they are enforceable.
Market participants should watch for:
- The guaranteed annual volume offered to European customers.
- The number and type of eligible buyers covered by the commitments.
- Contract duration and renewal rights.
- Pricing formulas and indexation mechanisms.
- Independent monitoring and reporting obligations.
- Whether the Commission requests a structural remedy in addition to supply guarantees.
MMG’s proposal gives the transaction a path toward approval, but it does not remove the core competition concern. The company must convince regulators that European customers will retain reliable access to ferronickel after the assets change hands : and that the promise can be tested and enforced long after the deal closes.
For now, the US$500 million transaction remains dependent on whether commercial guarantees can do the work of structural separation.
Source: Reuters reporting on MMG’s EU antitrust remedy offer; MMG transaction announcement.