Copper cathode sheets in an industrial refining circuit.

By Salini Krishnan
Mining investors are assessing the first session after the Federal Reserve raised interest rates by 25 basis points to a target range of 3.75%–4.00% in a unanimous 12-0 vote. Sixteen of 18 policymakers projected another hike.
Gold was trading near US$4,372 an ounce and silver near US$65.48, supported by easing Treasury yields. Yet the 10-year Treasury yield remains above 5%, keeping the opportunity cost of holding bullion elevated. At the same time, gold mining all-in sustaining costs have crossed US$1,500/oz, while Goldman Sachs retains a year-end gold view near US$4,900/oz.
The tension is central to this edition: higher spot prices do not automatically produce higher valuation multiples. For investors, the post-hike test is whether cash flows, project delivery and balance-sheet resilience can justify a rerating in P/NAV, or price-to-net asset value.
Market snapshot
| Market | Reference level | Investment read-through |
|---|---|---|
| LME copper | ~US$14,084/t | Strong pricing, but tariff positioning and stockpiling must be separated from end-user demand |
| SHFE copper | CNY107,740/t | Chinese pricing remains a key signal for regional demand and inventory flows |
| Gold | ~US$4,372/oz | Strong bullion margins are offset by higher rates, elevated costs and conservative long-term assumptions |
| Silver | ~US$65.48/oz | Industrial and monetary demand support the market, but volatility remains high |
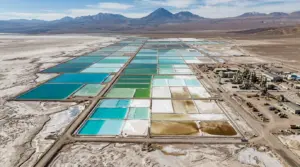
| Lithium carbonate | RMB140,000–185,000/t | Recovery depends on battery demand, inventory interpretation and the Jianxiawo restart |
| LME nickel | ~US$16,000/t | Indonesian RKAB ore quotas remain the central supply-floor variable |
| Uranium | ~US$90/lb | Term-market strength continues to support longer-cycle development interest |
| 10-year Treasury | Above 5% | Higher real yields increase the discount rate applied to mining assets |
Copper remains the central commodity thread. The market is pricing physical tightness, strategic stockpiling and the possibility of U.S. trade intervention. As discussed in Skillings’ copper price analysis, inventory location matters as much as the headline price.

The P/NAV scorecard
Gold equities still carry an estimated 40% discount to NAV, partly because many models use long-term gold assumptions of US$2,200–2,400/oz against spot prices above US$4,300/oz. That discount may appear striking, but it also reflects the difference between a spot price and a sustainable planning assumption.
| Segment | Indicative P/NAV | What investors must verify |
|---|---|---|
| Royalty and streaming platforms | 1.2x–2.0x | Counterparty quality, mine life, step-downs, buyback rights and production timing |
| Copper majors | 1.1x–1.2x | Permits, metallurgy, infrastructure and expansion capex |
| Mid-tier copper | 0.5x–0.8x | Funding runway, construction execution and processing route |
| Gold juniors and developers | 0.4x–0.6x | Permits, metallurgy, capex, financing and jurisdiction |
| Early-stage explorers | 0.3x–0.45x | Discovery quality, capital access and technical evidence |
| Recent M&A reference | ~0.73x deliverable NAV | Whether the transaction value reflects deliverable, rather than headline, NAV |
Royalty and streaming platforms continue to command a premium because they generally carry less direct exposure to labor, energy and sustaining-capital inflation. Their diversified portfolios can also capture exploration and expansion upside without funding every dollar of mine capex.
That premium does not make every royalty transaction attractive. Investors still need to test operator liquidity, contract enforceability, delayed-production risk and changing mine plans. A low P/NAV should be treated as a diligence trigger, not proof of undervaluation.

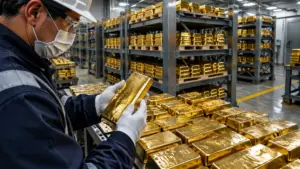
Gold doré production highlights the link between bullion prices, costs and deliverable cash flow.
Royalty and streaming deal flow
This week’s transactions show how royalty capital is being deployed across producing mines, development projects and smaller portfolio additions.
Empress Royalty agreed to acquire a gold stream on the Tongon gold mine in Côte d’Ivoire for US$62 million in cash. The purchase is funded by a US$75 million senior secured credit facility, with an initial US$55 million draw. Empress will receive 3.58% of payable gold production, stepping down to 2.93% and eventually 0.81% over a 29-year term. The agreement also includes contingent and participation payments.
Elemental Royalty finalized its acquisition of Vizsla Royalties at approximately C$327 million, comprising up to C$82 million in cash and about 8.1 million Elemental shares. Vizsla holders received roughly 11.19% of Elemental. The transaction secures 2.0%–3.5% life-of-mine NSRs over the Panuco silver-gold project in Mexico.
Franco-Nevada agreed to pay A$170 million to increase its Bullabulling gold royalty to approximately 3.90%, alongside a A$30 million equity subscription in Minerals 260. The combined commitment is A$200 million.
Vox Royalty completed an A$8.4 million acquisition covering the White Dam, Kalman and Sylvania Australian gold and copper royalties.
Chancery Royalty signed a non-binding term sheet for a US$20 million royalty financing with Fulcrum Metals, covering a 5% NSR on gold from the Teck-Hughes project in Ontario.
Across these deals, the key risks remain consistent: delayed production, operator liquidity, contract enforceability and changes to mine plans. Step-down provisions and buyback rights also materially affect the value of a royalty. A headline percentage is not enough; investors need to understand when the economics reduce and whether the operator can alter the underlying production profile.
M&A intelligence: strategic access over tonnes
Recent M&A activity reinforces the same valuation message. Buyers are paying for districts, processing routes, infrastructure, permitting status and strategic optionality: not simply headline resource tonnes.
Luca Mining agreed to acquire 100% of the El Barqueño gold-silver-copper project in Jalisco, Mexico, from Agnico Eagle for up to US$60 million plus a 2% NSR. The structure includes US$10 million in Luca shares at closing, US$30 million in milestone-linked payments and up to US$20 million tied to production milestones. Luca will have the right to repurchase half the royalty for US$12.5 million, with closing targeted for the fourth quarter.
Other transactions underline the strategic breadth of consolidation:
- Boliden agreed to acquire a controlling stake in Nexa in a €3.15 billion deal.
- Critical Metals agreed to acquire European Lithium for US$1.16 billion.
- Atlantis Lithium’s US$210 million takeover by Huayou is awaiting clearances.
- Lithium Argentina completed a US$180 million strategic investment from Ganfeng.
- First Au launched an A$46.5 million all-scrip takeover of Javelin Minerals.
- Glencore and InfraVia are examining a stake in Eramet’s lithium assets.

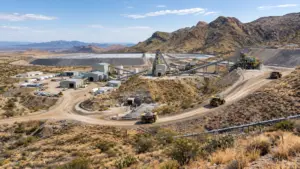
Mine infrastructure and processing access can be as important as the resource itself in M&A valuations.
The common theme is “buy versus build.” A permitted project near infrastructure may be more valuable than a larger but remote resource requiring a new processing route, power connection and lengthy approvals. That is why recent M&A has cleared at roughly 0.73x deliverable NAV, rather than at a uniform premium to in-ground resources.
Commodity price scenarios
| Commodity | Bear case | Base case | Bull case | Key catalyst |
|---|---|---|---|---|
| Copper | US$11,000–13,500/t | US$12,800–14,500/t | US$15,000–16,000/t | U.S. Section 232 decision expected around Sept. 30 |
| Lithium carbonate | Below working range if inventories rise | RMB140,000–185,000/t | Above range if Jianxiawo remains offline and battery demand strengthens | Jianxiawo restart and fourth-quarter demand |
| Nickel | Below US$16,000/t if quotas loosen | US$17,000–19,000/t | Upper end if Indonesian RKAB quotas tighten | Indonesian ore quotas |
| Uranium | Below US$90/lb if term demand weakens | Around US$90/lb | Higher on contracting and development-cycle strength | Term-market activity |
For copper, the bear case assumes tariff delays, a U.S. stockpile release, softer Chinese demand and stronger scrap flows. The base case assumes physical tightness persists while the policy premium moderates. The bull case requires tariffs to be implemented and ex-U.S. inventories to tighten. Citi’s bullish three-month target is near US$15,000/t, but U.S. inventory declines may reflect stockpiling rather than new consumption.
Lithium carbonate is working within a RMB140,000–185,000/t range. A methodology change lifted reported Chinese inventories to about 175,000 tonnes, which Macquarie described as information-driven rather than evidence of fundamental deterioration. The Jianxiawo restart and fourth-quarter battery demand remain the key variables.
Nickel is around US$16,000/t on the LME, with a scenario range of US$17,000–19,000/t. Indonesian RKAB ore quotas remain the supply floor. Uranium near US$90/lb continues to benefit from term-market strength and longer-cycle interest in development projects.
Investor checklist
Investors reviewing mining equities, royalty platforms or M&A targets should:
- Treat a low P/NAV as a diligence trigger, not proof of undervaluation.
- Test NAV using normalized prices below spot.
- Separate copper stockpiling from genuine end-user consumption.
- Compare transaction value with deliverable NAV.
- Review permits, metallurgy, infrastructure and remaining capex.
- Track funding runway and operator liquidity.
- Examine royalty step-downs, buyback rights and contingent payments.
- Monitor the dot plot, real yields and the U.S. dollar.
- Watch the Sept. 30 Section 232 window, the Jianxiawo review and Indonesian RKAB quotas.
The post-hike environment is not rejecting mining exposure. It is demanding greater proof that assets can deliver. For operators, that favors projects with permits, infrastructure and credible funding. For investors, the critical distinction is between a discounted asset with a pathway to production and a discounted asset whose risks are simply not yet reflected in the model.
Market information is provided for journalistic and educational purposes only. It is not financial advice or a recommendation to buy, sell or hold any security or commodity.
Social snippets
LinkedIn:
Mining investors are testing whether record commodity prices can translate into higher P/NAV multiples. Our latest Skillings Mining Intelligence edition examines royalty premiums, recent M&A clearing near 0.73x deliverable NAV, copper scenarios, lithium inventories and the post-hike valuation test.
X:
Spot prices do not automatically create higher mining multiples. We examine royalty streams, M&A premiums, P/NAV discounts and the copper, lithium, nickel and uranium catalysts investors are watching.
Lithium Power Map 2026 — Presale Now Open ($59). New data is reshaping the lithium supply chain for 2026. Reserve your copy of the Lithium Power Map at the presale price: https://skillings.short.gy/PowerMap