Copper’s sharp retreat from record highs is testing whether mining equities can hold their recent gains as traders reassess the timing of potential U.S. tariffs on refined metal.

Copper futures fell nearly 5% on Sept. 19 after the market pulled back from record levels, dragging London-listed miners lower. The move was driven less by a sudden change in mine fundamentals than by uncertainty over whether Washington will impose tariffs on refined copper and when those measures might take effect.
In the following session, copper rebounded in a sharp V-shaped move toward the 61.8% Fibonacci retracement near $6.6875 per pound. A sustained break above approximately $6.70/lb would put the market back into a test of its recent highs, while a failure to reclaim that level would leave miners exposed to further position unwinding.
The correction comes as global mined copper supply is on track for its first annual decline since 2017, according to analysis from Sprott Asset Management and data from the International Copper Study Group. That tension, weaker near-term price momentum against a deteriorating physical supply outlook, is now defining the copper market.
Tariff uncertainty triggered the selloff
The recent rally in copper futures was supported partly by expectations that U.S. tariffs would raise the domestic value of refined copper and encourage additional shipments into the United States.
That trade has become less certain. With no firm decision on the scope or timing of possible tariffs, traders have begun to reduce positions that assumed a large U.S. premium. The result was a rapid futures correction even though mine disruptions, lower ore grades and constrained concentrate availability remain unresolved.

The distinction matters for mining companies. Copper futures can move quickly when positioning changes, but mine supply responds over much longer time frames. A policy headline can remove several percentage points from the price in a session; replacing lost tonnes from a major mine can take years.
The London Metal Exchange copper contract remains the key benchmark for global pricing, but the tariff debate is also fragmenting the market by region. Metal drawn toward the United States could tighten availability elsewhere and create wider differences between U.S., European and Asian premiums.
Supply is weakening even as prices rise
The market’s fundamental backdrop remains unusually tight.
Sprott and ICSG data indicate that global mined copper output fell about 1.1% year over year in the first half of the year. If that trend continues, 2026 would mark the first annual decline in mined supply since 2017.
The decline reflects several overlapping problems:
- Major operational disruptions have removed expected production from the market.
- Chilean mines continue to contend with declining grades and aging infrastructure.
- Mature operations require more capital simply to maintain output.
- New copper projects face long permitting, financing and construction timelines.
- Smelters are competing for limited concentrate, pushing treatment charges to historic lows.
Sprott has highlighted disruptions at Grasberg in Indonesia and Kamoa-Kakula in the Democratic Republic of Congo as significant sources of lost production. Guidance reductions from producers including Antofagasta and Lundin Mining have added to concerns that expected supply growth will not materialize on schedule.
Chile remains central to the outlook. The country accounts for roughly one-quarter of global mined copper output, but first-half production was reported to be down sharply from the previous year. Lower grades, water constraints, deeper ore bodies and maintenance requirements have limited the ability of producers to increase output even when prices are near records.
Cochilco has cut its 2026 Chilean production forecast to approximately 5.27 million tonnes, according to market reporting cited in Sprott’s analysis. That would leave the world’s largest copper producer below its recent output potential.

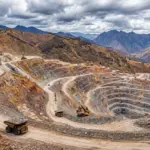
Large-scale open-pit operations require sustained investment to offset lower grades and deeper mining conditions.
Chinese buying is sending a stronger signal
The physical market in China is providing an important counterweight to the futures selloff.
The Yangshan copper premium, which measures the premium paid for imported refined copper delivered into the bonded zone near Shanghai, rebounded to roughly $118-$121 per tonne in mid-September, according to market reports from SMM and Metal.com.
That recovery suggests Chinese buyers returned to the market after prices eased. The premium had softened earlier as high prices caused some downstream consumers to delay purchases. Once copper retreated, buyers appeared more willing to replenish inventories.
The Yangshan premium is not a perfect measure of end-use demand. It can also reflect import economics, exchange-rate movements, local inventories and the availability of cargoes. Even so, a move toward four-year highs indicates that the physical market is tighter than the recent futures correction might suggest.
This creates a two-speed copper market:
| Indicator | Latest signal | Market implication |
|---|---|---|
| Copper futures | Rebounded toward $6.6875/lb | Technical support remains under review |
| Key technical level | Approximately $6.70/lb | A break above could reopen upside momentum |
| Global mined supply | H1 output down about 1.1% year over year | 2026 could mark the first annual decline since 2017 |
| Yangshan premium | Roughly $118-$121/t in mid-September | Chinese physical buying has strengthened |
| Chilean production | Below recent potential | Lower grades and aging assets remain structural risks |
| Treatment charges | At exceptionally low or negative levels | Smelters are competing for scarce concentrate |
Treatment and refining charges offer another indication of pressure in the supply chain. Spot charges have moved into negative territory in parts of the market, while the 2026 annual benchmark was reported at zero. Normally, miners pay smelters to process concentrate. When charges collapse, it signals that smelters have limited negotiating power because feedstock is scarce.
The Skillings analysis of the copper supply squeeze examines how mine underperformance, low treatment charges and grid-related demand are converging.
What the pullback means for copper producers
The market reaction across the producer peer group is likely to remain uneven. A futures decline affects all copper exposure, but the financial impact depends on operating costs, hedging, mine life, jurisdiction and balance-sheet strength.
Large diversified producers
Companies such as BHP and Rio Tinto offer diversified exposure across several commodities. That can reduce the impact of a single copper mine disruption, but it also means their equity performance is not a pure copper trade.
For these companies, investors will focus on whether higher copper prices can offset cost inflation, declining grades and large capital requirements. The market will also watch project execution, particularly at expansion projects intended to replace mature production.
Major copper-focused producers
Freeport-McMoRan, Southern Copper, Antofagasta and Lundin Mining generally offer more direct sensitivity to copper prices. That can support stronger earnings leverage when prices rise, but it also increases exposure to mine-specific interruptions, regional permitting risk and changes in operating guidance.
The key distinction is between headline copper prices and realized cash margins. A producer with high costs, heavy sustaining capital requirements or significant disruption risk may not benefit as much as the benchmark price suggests.
Developers and emerging producers
Copper developers typically carry greater price sensitivity because their valuations depend on future construction decisions, financing costs and project economics rather than current production.
A sustained copper price above the $6.70/lb technical level could improve project studies and financing discussions. However, developers remain vulnerable if the market begins to treat the recent rally as speculative or if tariffs and regional premiums complicate assumptions about future concentrate and refined-metal pricing.
For this group, the most important indicators are not only the copper price but also permitting progress, capital intensity, infrastructure access, expected recovery rates and the timeline to first production.
The Skillings copper category tracks developments across producers, projects and policy.
Base, bull and bear cases
The market’s next phase will depend on whether physical tightness or policy uncertainty has greater influence.
| Scenario | Copper market conditions | Likely implication for miners |
|---|---|---|
| Base case | Copper holds near recent highs but remains volatile as tariff details emerge; supply growth stays weak and Chinese buying remains price-sensitive | Producers retain margin support, but equities trade selectively around guidance and valuation |
| Bull case | Copper breaks above $6.70/lb, Yangshan premiums remain elevated and major disruptions persist | Cash-flow leverage strengthens, while developers receive more favorable project economics |
| Bear case | Tariff expectations fade, Chinese demand weakens and speculative positions continue to unwind | High-cost producers and developers face sharper valuation pressure despite long-term supply concerns |
The immediate technical test is clear: copper needs to regain and hold approximately $6.70/lb to show that the pullback was primarily a positioning event. A failure to do so would leave the market vulnerable to another leg lower.
The longer-term test is more difficult. The industry must replace declining output from mature mines while developing new capacity in jurisdictions where permitting, water, power and community approvals can take many years.
The market is separating price from supply
Copper’s five-percent pullback does not erase the supply problem. It does, however, remind investors that mining shares can react more violently than the metal itself.
The near-term market will be driven by tariff headlines, technical positioning and Chinese buying. The medium-term market will depend on whether disruptions persist, whether Chile can stabilize output and whether new projects advance quickly enough to offset falling grades.
For operators, the message is that high prices do not remove execution risk. For investors and analysts, the more useful question is not simply whether copper remains expensive, but which companies can convert elevated prices into durable production and free cash flow.
At present, the market is still balancing two conflicting signals: a futures curve shaken by policy uncertainty and a physical market that continues to show signs of scarcity. Until one of those signals breaks decisively, copper producers and developers are likely to remain highly sensitive to every move around the $6.70/lb level.

Copper cathodes move through an industrial processing and storage facility.

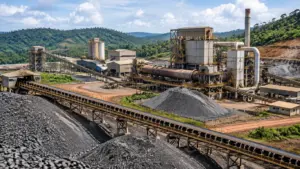
Mine infrastructure links extraction, processing and transport in a dry copper-producing region.
Sources: Sprott Asset Management, London Metal Exchange, SMM market report via Metal.com, and Skillings Mining Review.