Copper cathodes and coils move through a port logistics terminal.

By Penny Langford
Copper prices surged on Sept. 22 as the market absorbed a widening gap between expected mine supply and demand, alongside increasingly tight exchange inventories.
Comex copper rose 3.3% intraday to US$6.841 per pound, while three-month LME copper reached US$14,710.50 per metric ton. Both contracts remained less than 2% below record highs, according to market coverage from Mining.com and analysis cited by Geomechanics.io.
The immediate catalyst is a roughly 600,000-tonne reduction in expected 2026 mine output following unplanned disruptions at Freeport-McMoRan’s Grasberg operation in Indonesia and Ivanhoe Mines’ Kamoa-Kakula complex in the Democratic Republic of Congo. Global copper mine production is now expected to decline in 2026 for the first time since 2017.
That supply shock is meeting a physical market that is becoming harder to source. But the rally is not without friction. Copper’s record run lasted only five days before investors began questioning whether the shortage narrative is fully supported by underlying demand.

Copper market snapshot
The latest figures show a market tightening across both physical availability and exchange positioning.
| Indicator | Latest signal | Why it matters |
|---|---|---|
| Comex copper | US$6.841/lb, up 3.3% intraday | Prices are testing record levels |
| LME copper | US$14,710.50/t | Less than 2% below the record high |
| LME on-warrant stocks | 133,725t | Metal immediately available for delivery |
| Cancelled LME warrants | 115,450t, or 45% of warehouse stocks | Material scheduled withdrawals could reduce available supply |
| LME cash spread | From US$86/t contango to US$26/t backwardation | Nearby metal has become more valuable than deferred supply |
| Comex warehouse stocks | 696,204t, about 69% of monitored copper | Inventory is concentrated in the U.S. market |
| Yangshan premium | US$124/t, easing to US$119/t | Chinese buyers are still paying elevated import premiums |
| Expected 2026 mine-output reduction | About 600,000t | Disruptions have materially altered the supply outlook |
The most closely watched change is the movement in LME stocks. On-warrant inventory has fallen to 133,725 tonnes from total LME warehouse holdings of 255,900 tonnes. A further 115,450 tonnes is already tied to cancelled warrants and scheduled for withdrawal.
Cancelled warrants do not guarantee that every tonne will immediately leave the warehouse. They do, however, signal that metal holders have requested removal. At 45% of total LME warehouse stocks, the figure has become an important measure of how much visible inventory may be unavailable to the market in the weeks ahead.
The cash market has also shifted sharply. LME cash copper moved from an US$86-per-tonne discount to a US$26-per-tonne backwardation within a week. That change indicates that buyers are placing a premium on prompt delivery rather than waiting for later supply.
Comex stocks are high, but not necessarily comfortable
Comex warehouses hold 696,204 tonnes, representing roughly 69% of exchange-monitored copper. That total has helped prevent an immediate global inventory crisis, but its location matters.
A large share of the metal is concentrated at the Port of New Orleans, where storage is described as largely full. Another 100,000 tonnes from Africa and South America is expected to arrive by October, creating a logistical problem even if the metal is technically available.
Comex stocks recorded their first weekly decline since April, falling by 65 tonnes. The decline is small compared with total inventory, but the direction is significant because it interrupts a long period of accumulation.
The market is therefore dealing with two different questions:
- Is there enough copper globally?
- Is enough copper available in the right location and form, at the right time?
Those questions are increasingly producing different answers. Material may exist in transit, at ports or in regional warehouses, while nearby consumers face higher premiums for deliverable units.
The Yangshan premium illustrates that regional tightness. It reached US$124 per tonne, a near four-year high, before easing to US$119 per tonne. The premium remains elevated even as copper prices test records, suggesting that Chinese buyers are competing for seaborne units rather than simply responding to futures-market momentum.

Copper cathodes move through a refinery beside active smelting equipment.
The 600,000-tonne supply gap changes the 2026 outlook
The supply shock is concentrated in two important operations.
Freeport’s Grasberg mine and Ivanhoe’s Kamoa-Kakula complex were both expected to contribute significant volumes to global mine supply. Operational disruptions at the projects have removed approximately 600,000 tonnes from earlier 2026 expectations.
That is large enough to change the market balance, particularly because new copper supply is slow to replace. A mine cannot normally respond to higher prices within a few quarters. Permitting, construction, infrastructure and commissioning often take years, while brownfield expansions remain exposed to declining grades, equipment constraints and labor risks.
Planned maintenance at Chinese refineries during October and November could further restrict refined output into year-end. Congestion at Shanghai ports is also making it more difficult to determine when seaborne copper will reach consumers.
The combination creates a potential bottleneck across three stages:
- Mine supply is falling below expectations.
- Refined output may be constrained by maintenance.
- Logistics are delaying the movement of available material.
This is the basis for the bullish argument. It does not require global demand to accelerate dramatically. A market can tighten if supply falls faster than consumption.
Demand remains the market’s main uncertainty
Copper’s structural demand case remains strong. The metal is central to power-grid expansion, renewable generation, electric vehicles, data centers, industrial automation and domestic manufacturing investment.
The United States is particularly exposed. Copper was added to the U.S. Geological Survey’s 2025 Critical Minerals List for the first time. The USGS 2026 copper summary also shows significant U.S. import dependence, with net import reliance estimated at 57% of apparent consumption for 2025. Earlier USGS data showed a 38% figure, while industry estimates for refined copper reliance have placed exposure above 40%.
That dependence is becoming more consequential as Washington seeks to expand domestic manufacturing and strengthen critical-mineral supply chains.
New domestic projects will be judged against this backdrop. White Pine Copper’s Michigan project provides one example of the economic profile needed to attract capital. Its preliminary feasibility study reported a post-tax net present value of about US$1.38 billion and an all-in sustaining cost of US$2.32 per pound, placing the project in the first quartile of the U.S. copper cost curve, according to project information and coverage summarized by Highland Copper.

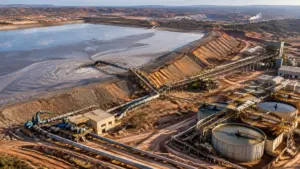
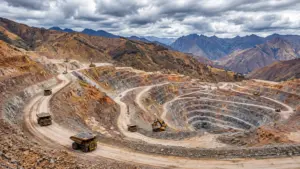
Open-pit copper mining operations connect extraction with processing infrastructure.
The project economics are notable because high copper prices alone will not guarantee new supply. Developers also need competitive costs, infrastructure, permitting visibility and financing capacity.
Technology may provide another route to margin protection. First Quantum Minerals’ 2025 climate report describes its Quantum Electra-Haul trolley-assist system, which can reduce diesel consumption by up to 90% on uphill haulage segments. The company reported approximately 14 kilometers of trolley lines installed in Zambia and nearly 500,000 kilometers of trolley-assisted hauling in 2025.
That technology does not solve the global supply deficit by itself. It does show how copper producers are attempting to lower energy intensity and preserve margins as mines become deeper, haul distances lengthen and fuel costs remain volatile. The company’s 2025 Climate Change Report also links trolley assist to future battery-electric haulage.
Copper price forecast: base, bull and bear cases
The following framework is a scenario analysis rather than an investment recommendation. It reflects the interaction between mine disruptions, exchange stocks, refined production, logistics and end-use demand.
| Scenario | 2026 price range | Core assumptions | Main risk |
|---|---|---|---|
| Base case | US$12,000–14,000/t average | Supply remains tight, but demand growth slows; Chinese refinery maintenance is temporary; stocks stabilize above critical levels | Demand fails to absorb high prices |
| Bull case | US$14,000–17,000/t, with higher spikes possible | The 600,000t supply loss persists, cancelled warrants become physical withdrawals, Chinese premiums remain elevated and demand from grids and data centers holds | Substitution, demand destruction or inventory releases |
| Bear case | US$10,000–11,500/t | Mine disruptions are repaired faster than expected, refined output recovers and global manufacturing weakens | A visible surplus rebuilds across exchanges |
The base case assumes copper remains historically expensive but does not move in a straight line. Prices could stay above the levels used in many earlier forecasts while still retreating from current records if demand weakens.
The bull case depends less on a new demand boom than on the failure of supply to respond. A persistent drawdown in exchange stocks, combined with backwardation and regional premiums, would increase the probability of short-term spikes.
The bear case is not limited to a global recession. Copper demand could weaken simply because high prices delay purchases, encourage substitution or cause manufacturers to draw down private inventories. That is the central tension in the current market.
What operators and investors should watch next
Four indicators will help determine whether the rally reflects a durable physical shortage or a temporary squeeze:
- LME cancelled warrants: Large withdrawals would confirm that visible stocks are becoming less available.
- Comex inventory direction: A sustained decline would matter more than the initial 65-tonne weekly fall.
- Yangshan premiums and Shanghai congestion: These offer a real-time view of Chinese import demand and delivery friction.
- Mine-recovery timelines: Updates from Grasberg and Kamoa-Kakula will determine whether the 600,000-tonne loss is temporary or structural.
The market is also likely to watch whether high prices begin to alter demand. Copper’s role in electrification, grid modernization and data centers supports long-term consumption, but infrastructure projects can be delayed and procurement can be rescheduled when prices rise sharply.
Bottom line
The 2026 copper outlook has shifted toward tighter supply and greater price volatility. A roughly 600,000-tonne reduction in expected mine output, falling immediately available LME stocks, elevated Chinese premiums and a return to backwardation have created the conditions for a stock squeeze.
But tight physical indicators do not remove demand risk. The record run’s rapid reversal shows that investors remain unconvinced that every bullish supply signal will translate into sustained consumption.
For decision-makers, the most useful forecast is not a single number. It is a range shaped by inventory availability, mine-recovery schedules, refinery operations and the ability of electrification-related demand to absorb elevated prices.
LinkedIn snippet
Copper is testing record highs as a roughly 600,000-tonne reduction in expected 2026 mine output meets tightening exchange stocks, LME backwardation and elevated Chinese premiums. Our latest analysis examines the base, bull and bear cases, and why demand remains the market’s key uncertainty.
X snippet
Copper’s 2026 outlook is tightening: a roughly 600,000t mine-output gap, falling LME on-warrant stocks, backwardation and a near four-year-high Yangshan premium are driving the rally. But high prices could still weaken demand. Read the base/bull/bear framework.