By Penny Langford

Lithium prices have recovered sharply from last year’s lows, but the market is now testing whether stronger benchmarks can translate into durable project economics. A Chinese lithium carbonate benchmark tracked by Benchmark Mineral Intelligence and reported by The Wall Street Journal reached US$23,150 per tonne on Sept. 2, up from US$10,900/t a year earlier.
The rebound has improved the outlook for producers and developers. It has also raised the cost of being wrong about supply. A futures-led selloff in China hit listed lithium companies hard in the latest week, while exploration results from Nevada and Brazil showed why resource scale must still be separated from mineable, processable supply.
The central question for the 2026 lithium price forecast is not whether demand is growing. It is whether new supply can arrive with the required grade, metallurgy, infrastructure and timing.
The price rebound meets a volatile futures market
The move from US$10,900/t to US$23,150/t represents an increase of about 112% in the Chinese benchmark over one year. The price recovery reflects a market that has absorbed production curtailments, project delays and renewed demand from electric vehicles and energy storage.
However, prices have not moved in a straight line. A selloff in GFEX lithium carbonate futures placed pressure on the wider sector, with lithium producers recording substantially larger equity declines than the underlying commodity move:

| Market marker | Reported level or move | Why it matters |
|---|---|---|
| Chinese lithium carbonate benchmark | US$23,150/t | September price reference reported by The Wall Street Journal |
| Comparable benchmark one year earlier | US$10,900/t | Shows the scale of the annual recovery |
| Elevra Lithium | Down 17.2% | Equity sensitivity to futures and project assumptions |
| PLS Group | Down 14.7% | Producer exposure to realized spodumene prices |
| Liontown | Down 13.0% | Development and ramp-up sensitivity |
| IGO | Down 12.4% | Diversified exposure still affected by lithium sentiment |
The equity response shows how quickly investors can reprice future cash flows when futures weaken. A short-term decline does not necessarily change long-term demand, but it can affect project financing, expansion schedules and the valuation of higher-cost operations.
Skillings has previously examined the effect of hard-rock curtailments and delayed capacity in the lithium market. The same issue remains relevant: announced capacity is not equivalent to delivered battery-grade material.
Demand remains the structural support
The International Energy Agency’s 2026 outlook projects lithium demand rising more than threefold by 2040 under its Stated Policies Scenario. The agency also finds that expected supply from announced projects has narrowed the projected gap.
That narrowing is important, but it does not eliminate the risk. Announced projects still face permitting, capital, construction, infrastructure and processing hurdles. The IEA’s critical-minerals analysis distinguishes between what companies have announced and what the market can realistically deliver at the required time.
Energy storage adds another layer to the demand outlook. Lithium iron phosphate batteries, widely used in stationary storage and parts of the electric-vehicle market, rely heavily on lithium carbonate. Growth in grid batteries therefore broadens lithium demand beyond passenger EV sales.
For operators and policymakers, the implication is straightforward: annual demand forecasts matter, but the market can tighten earlier if supply is delayed by even a small number of major projects.
New supply is arriving through different geological routes
The current project pipeline illustrates the diversity of lithium supply, and the different risks attached to each project type.
Ewoyaa puts ownership and supply-chain control in focus
Huayou Cobalt has cleared a key hurdle in its proposed acquisition of Atlantic Lithium, which controls the Ewoyaa project in Ghana. The transaction values Atlantic Lithium at approximately US$210 million and would give Huayou control of a project with a reported resource of about 36.8 million tonnes grading 1.24% Li₂O, equivalent to roughly 1.1 million tonnes of lithium carbonate equivalent.
The deal also includes a commitment by Huayou to assume the remaining development funding obligations for Ewoyaa. That structure matters because access to capital is one of the principal risks facing development-stage lithium projects.
The transaction is also strategically significant. It links a West African hard-rock asset to a major Chinese battery-materials producer, reinforcing the importance of ownership, conversion capacity and logistics in the global critical-minerals race.
Read more about the Huayou Cobalt and Atlantic Lithium transaction.

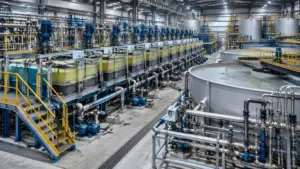
Processing capacity and recovery rates determine how much hard-rock resource can become battery-grade supply.
Red Mountain adds scale, but the resource category matters
Venari Minerals’ Red Mountain project in Nevada has a 3.03-million-tonne lithium carbonate equivalent inferred resource. The company has also outlined a broader exploration target of 10.7–18.6 million tonnes LCE.
The figures are substantial, but the distinction between an inferred resource and an exploration target is essential. An inferred resource is an early resource category with limited geological confidence. An exploration target is conceptual and requires additional work before it can be classified as a mineral resource.
Red Mountain also carries potential by-product value through strontium. The United States currently imports 100% of its strontium, according to the project information supplied for this analysis. If technical work confirms recoverable quantities and a viable processing route, the by-product could improve project economics and strengthen the domestic critical-minerals case.
The next questions are therefore metallurgical as much as geological: recovery rates, clay processing, reagent consumption, water requirements and the ability to produce consistent carbonate at commercial scale.
Igrejinha tests what lies beneath weathered cover
In Brazil, Perpetual Resources is mobilising a diamond rig for approximately 22 holes and 1,500 metres at its Igrejinha project in Minas Gerais.
The drilling is designed to test pegmatites beneath weathered cover. Surface rock-chip samples returned results of up to 7.6% lithium oxide, while earlier weathered reverse-circulation drilling produced more modest grades.
That contrast is a reminder of why surface samples cannot be treated as a proxy for a mine plan. A high-grade rock chip may identify a promising pegmatite, but diamond drilling must establish continuity, thickness, mineralogy and the relationship between weathered and fresh rock.

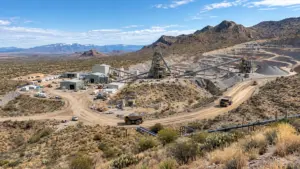
Perpetual Resources is testing pegmatites beneath weathered cover at Igrejinha in Minas Gerais.
Lithium price scenarios
The price framework below uses the US$23,150/t Chinese benchmark as the current reference point. It is not a price target or investment recommendation. The scenarios illustrate how supply delivery and demand growth could alter the market balance.
| Scenario | Indicative carbonate range | Supply assumptions | Demand assumptions | Market outcome |
|---|---|---|---|---|
| Bear case | US$14,000–18,000/t | Announced projects ramp on schedule; higher-cost mines restart; processing bottlenecks ease | EV growth moderates and storage deployment is uneven | Surplus returns and inventories rebuild |
| Base case | US$18,000–25,000/t | Supply expands selectively; Ewoyaa and other projects advance, but delays remain | EV demand remains firm while storage adds steady carbonate consumption | Market stays volatile and broadly balanced |
| Bull case | US$25,000–32,000/t | Weathered-cover and clay projects take longer; hard-rock restarts remain limited; permitting delays persist | Storage accelerates and EV demand exceeds current assumptions | Tightness returns and qualified carbonate attracts premiums |
The base case reflects a market in which the current price recovery supports development, but does not immediately solve the supply problem. The bull case requires more than strong demand: it requires project execution to fall short across several regions at once.
What decision-makers should monitor
The most important indicators through 2026 will be operational rather than purely financial:
- Chinese inventory quality and location: Reported tonnes are not necessarily available for immediate battery-grade delivery.
- GFEX futures structure: Persistent backwardation or renewed volatility would signal changing expectations around near-term supply.
- Ewoyaa’s approval and funding timeline: Huayou’s sole-funding commitment could reduce one major development risk, but construction and permitting remain.
- Red Mountain metallurgy: The project’s scale must be tested against clay-processing recovery, water and reagent requirements.
- Igrejinha drill results: The key issue is continuity beneath weathered cover, not the highest individual surface sample.
- Energy-storage demand: LFP battery output will remain an important driver of carbonate consumption.
- Restarts and curtailments: Higher-cost hard-rock operations may return only if prices provide sufficient margin after processing and logistics costs.
The lithium market has entered 2026 with a much stronger price signal than it had a year earlier. Yet the latest futures selloff shows that sentiment remains fragile. The price recovery can encourage new supply, but it can also expose the difference between a large geological inventory and material that is permitted, financed, processed and delivered.
For now, the most defensible outlook is a wide trading range centered near the high teens to mid-US$20,000s per tonne. Demand growth provides the long-term foundation. Weathered-cover drilling, clay processing, project funding and the speed of new supply will determine how much of that foundation reaches the market.
LinkedIn snippet
Lithium carbonate reached US$23,150/t, more than double its level a year earlier, but GFEX volatility has exposed the sector’s sensitivity to supply expectations. Our analysis compares Huayou’s Ewoyaa deal, Venari’s Red Mountain resource and Perpetual Resources’ weathered-cover drilling at Igrejinha across base, bull and bear cases.
X snippet
Lithium’s 2026 outlook is caught between a US$23,150/t benchmark and execution risk. Ewoyaa adds funded Ghanaian supply, Red Mountain adds Nevada scale, and Igrejinha must prove pegmatite continuity beneath weathered cover. The base case remains volatile, not settled.
Sources and further reading
- IEA Global Critical Minerals Outlook
- IEA Global Critical Minerals Outlook 2025
- Benchmark Mineral Intelligence lithium prices
- Huayou Cobalt and Atlantic Lithium transaction
- Venari Minerals Red Mountain resource announcement
- Venari Minerals Red Mountain exploration target
- Lithium market supply discipline and hard-rock curtailments
- Lithium inventory and supply-discipline analysis