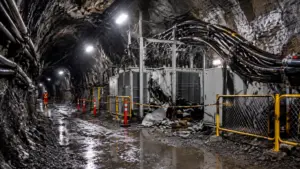
Nevada mine and processing infrastructure illustrate the producing assets attracting royalty and streaming capital.

By Salini Krishnan
Mining M&A deals in 2026 are increasingly being priced around what projects can deliver, rather than the size of their headline resources. The latest transactions involving Elemental Royalty, Luca Mining and Artemis Gold show how buyers are using structured consideration, equity financing and permitted infrastructure to navigate a sharp reset in price-to-net asset value, or P/NAV.
The distinction matters for investors. A low P/NAV can indicate an overlooked asset, but it can also reflect delayed production, weak counterparties, uncertain contracts, permitting risk or an unfinanceable mine plan. Recent deals suggest that strategic buyers are willing to pay for deliverable ounces and pounds when the pathway to production is sufficiently clear.
Market snapshot
| Market | Reference level | Investment read-through |
|---|---|---|
| LME three-month copper | About US$14,650/t | Near record levels, but stockpiling and tariff positioning must be separated from end-user demand |
| Copper TC benchmark | Zero in 2026 vs. US$21.25/t in 2025 | Concentrate scarcity is tightening smelter economics |
| Gold | About US$4,336/oz | Strong spot margins contrast with conservative long-term NAV assumptions |
| Silver | About US$65.70/oz | Persistent deficit supports a US$75–85/oz base case and US$100/oz bull case |
| Lithium carbonate futures | About CNY132,500/t | 2026 base case of CNY130,000–170,000/t |
| Nickel | Above US$18,000/t | Indonesian RKAB quotas remain the supply-floor variable |
| Uranium | US$89.75/lb spot; US$96.50/lb term | Contracting strength precedes a projected 18% demand deficit in 2027 |
| Iron ore | Below US$95/t | Chinese steel-mill output cuts remain the principal pressure |
LME copper reached a record US$14,703 per tonne on Sept. 8 before retreating toward US$14,065/t. The market remains supported by tight concentrate availability: the 2026 annual treatment charge benchmark has fallen to zero, compared with US$21.25/t in 2025, while spot charges have moved deeply negative.
That backdrop is positive for copper producers with operating leverage, but it does not eliminate execution risk. The market is also watching the timing and scope of potential U.S. Section 232 copper measures, which could encourage stockpiling without necessarily proving stronger underlying consumption.

Elemental Royalty expands its producing portfolio
Elemental Royalty has agreed to acquire five streams and royalties from funds managed by Orion Mine Finance for US$290 million.
The consideration comprises US$200 million in cash and US$90 million in Elemental shares, representing 4,289,053 shares, or about 5.6% of shares outstanding. Three of the five assets are producing:
- A 50% silver stream on i-80 Gold’s Ruby Hill Complex and Granite Creek in Nevada.
- A 5% gold stream on Mansa Resources’ Kouroussa mine in Guinea.
- A 2.5% gross revenue royalty on Silverco Mining’s La Negra mine in Mexico.
- A 1% gold stream on Endura Mining’s Snowy River project in New Zealand.
- A 1% NSR royalty over Dakota Gold’s ground in South Dakota’s Homestake District.
The contract terms are central to the valuation. The Ruby Hill stream steps down to 10% after 2.5 million ounces of silver have been delivered, with approximately 1.3 million ounces remaining. The Kouroussa stream falls from 5% to 2.5% at the later of November 2037 or 39,800 ounces delivered. Mansa also has a one-time right to buy back half the stream for US$22.5 million before November 2028.
Elemental is funding the cash component partly by expanding its National Bank of Canada revolving facility from US$150 million to US$250 million. The company said the Orion assets will contribute economically from Aug. 1, subject to closing, which is targeted for the fourth quarter.
Elemental has raised 2026 guidance to 19,500–22,000 gold-equivalent ounces, including approximately 1,500 ounces from the Orion portfolio. Revenue guidance is US$89.8 million–US$101.1 million, assuming gold at US$4,500/oz. Its shares last traded at C$30.45.
The transaction is paired with a divestment of Elemental’s generation business to Carlin East Inc. for stock valued at US$8.5 million, representing about 19.9% of Carlin East after financing. Elemental will retain half of the production royalties on transferred agreements. Management expects headcount to fall by more than 50% and annual cash costs to decline by about US$6 million, or roughly 25% of projected spending.
David Cole will resign as CEO to become executive chair of Carlin East, while founder Frederick Bell returns as Elemental’s CEO. Snowy River’s first gold target is December 2026, although the company has warned that production could slip into the first quarter of 2027.
The deal illustrates why royalty and streaming companies continue to trade at a premium: they gain exposure to metal prices and mine growth while avoiding much of the operating and sustaining-capital burden carried by mine owners. That premium only holds, however, if counterparties remain solvent and contract step-downs are properly reflected in NAV models.
Luca turns Cozamin into a structured copper bet
Luca Mining’s proposed acquisition of Capstone Copper’s Cozamin mine in Zacatecas, Mexico, values the asset at up to US$385 million.
Under the agreement, Capstone will receive US$275 million in upfront cash, US$15 million in Luca shares, US$35 million in deferred consideration payable on the first anniversary of closing and up to US$60 million in contingent cash linked to average annual LME copper prices from 2027 through 2029.
Cozamin has reserves of 6.7 million tonnes grading 1.40% copper and 42.2 grams per tonne silver. The mine plan extends to 2030. Luca expects the acquisition to increase 2027 net revenue to about US$598 million from US$177 million in 2025, with operating cash flow of roughly US$223 million compared with US$37 million.
The financing package includes:
| Financing component | Amount | Structure |
|---|---|---|
| Bought deal | US$110M | Backed by a US$75M Trafigura equity backstop |
| Concurrent placement | US$40M | With Wheaton Precious Metals and Taurus Mining Finance |
| Senior secured facility | US$125M | Provided by Taurus and Macquarie |
| Additional silver stream | US$25M | Wheaton receives incremental 15% of refined silver up to 500,000 oz |
The silver stream is capped and incremental. Wheaton will receive 15% of refined silver in addition to the mine’s existing 50% stream until 500,000 ounces have been delivered. Payments for the additional stream will equal 10% of the spot silver price.
The contract structure offers a useful lesson for mining M&A. Contingent consideration allows the buyer to limit commodity exposure at closing while giving the seller additional upside if copper prices remain strong. It also shifts part of the valuation debate from current NAV to the quality of the price-linked payment mechanism.
Artemis buys permitted ounces with equity
Artemis Gold has agreed to acquire Vista Gold in an all-share transaction valued at approximately US$427 million. Vista shareholders will receive 0.0966 Artemis shares for each Vista share, implying consideration of about US$2.83 per Vista share and a 29% premium to the 20-day VWAP.
The asset is Vista’s permitted Mt Todd gold project in Australia’s Northern Territory. Mt Todd contains approximately 9.1 million ounces of Measured and Indicated resources and 1.4 million ounces of Inferred resources. Permits are in place for a 50,000-tonne-per-day processing facility.
Artemis expects Blackwater’s Phase 1A and EP2 expansion to remain its priority. Construction capital for Mt Todd is not expected to be required before EP2 is completed, allowing the company to defer major spending while advancing engineering, permitting and project optimization.
Closing is expected in January, subject to shareholder, court, FIRB and Northern Territory ministerial approvals. Existing Artemis shareholders are expected to own about 95% of the combined company, with Vista shareholders holding about 5%.
The transaction reflects a wider preference for permitted and de-risked ounces. In a market where developers often trade below 0.6x P/NAV, acquiring an approved project with nearby infrastructure can be more efficient than building a new resource base from exploration stage.
The P/NAV scorecard
| Segment | Indicative P/NAV | Primary diligence question |
|---|---|---|
| Royalty and streaming platforms | 1.2x–2.0x | Are counterparties strong and step-downs properly valued? |
| Copper majors | 1.1x–1.2x | Can growth projects meet permitting and capital targets? |
| Mid-tier copper producers | 0.5x–0.8x | Is funding sufficient through construction and ramp-up? |
| Gold juniors and developers | 0.4x–0.6x | Are permits, metallurgy and capex credible? |
| Early-stage explorers | 0.3x–0.45x | Is there enough technical evidence to justify future funding? |
| Recent M&A reference | About 0.73x deliverable NAV | Does the deal value reflect financeable production? |
Gold equities are often modeled using long-term prices of US$2,200–2,400/oz, compared with spot near US$4,336/oz. That difference produces an estimated 40% discount to modeled NAV, but the discount should not automatically be treated as mispricing. Conservative assumptions may protect against a reversal in bullion prices, while delayed production, inflation and financing costs can reduce the value of even a large resource.
Investors should normalize NAV below spot and distinguish deliverable NAV from headline resource value. A project with permits, infrastructure and known metallurgy deserves a different risk assessment from an early-stage discovery with no defined development route.
Commodity scenarios
| Copper case | Price range | Main assumptions |
|---|---|---|
| Bear | US$10,500–13,000/t | Softer Chinese demand, delayed tariffs, stronger scrap flows and inventory release |
| Base | US$13,000–15,000/t | Persistent physical tightness with a moderating policy premium |
| Bull | Above US$15,000/t | Tight ex-U.S. inventories, tariff implementation and constrained mine supply |
Silver’s 2026 base range is US$75–85/oz, with a bull case near US$100/oz if the structural deficit persists. Lithium carbonate futures near CNY132,500/t compare with spot indications of CNY130,000–143,000/t, while the base case is CNY130,000–170,000/t. Nickel’s base case remains above US$18,000/t if Indonesian RKAB quotas limit ore supply.
Uranium spot at US$89.75/lb and term pricing at US$96.50/lb point to continued contracting support, particularly ahead of an expected 18% demand deficit in 2027. Iron ore below US$95/t remains exposed to Chinese steel production cuts.
Investor checklist
Investors reviewing mining M&A deals, royalty platforms or critical minerals projects should:
- Normalize NAV using long-term prices below spot.
- Compare transaction value with deliverable NAV.
- Examine royalty step-downs, buyback rights and contingent payments.
- Test funding runway through construction and ramp-up.
- Review permits, infrastructure, metallurgy and remaining capex.
- Assess counterparty liquidity and contract enforceability.
- Separate stockpiling from genuine end-user demand.
- Monitor the Section 232 copper tariff window.
- Track Indonesian RKAB quotas, lithium supply restarts and uranium contracting.
The current P/NAV reset is rewarding assets that can move from balance sheet to production with limited friction. The central question for investors is not simply whether an asset is cheap. It is whether the discount compensates for the risks still standing between the resource and the cash flow.
Market information is provided for journalistic and educational purposes only. It is not financial advice or a recommendation to buy, sell or hold any security or commodity.
Social snippets
LinkedIn: Mining M&A in 2026 is increasingly being priced around deliverable NAV. Our latest Skillings Mining Intelligence briefing examines Elemental Royalty’s US$290 million portfolio acquisition, Luca Mining’s structured Cozamin deal, Artemis Gold’s Mt Todd transaction and the commodity assumptions driving the P/NAV reset.
X: Mining valuations are separating assets that can deliver from assets that only look cheap on paper. We examine royalty step-downs, contingent M&A payments, permitted gold ounces and copper, lithium, nickel and uranium scenarios.
2026 Lithium Power Map presale: $59
Pre-order: https://buy.stripe.com/fZu28rafU7nx8O44aeaEE08