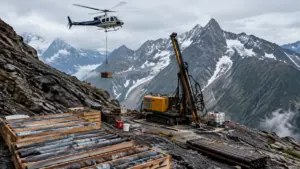
Nevada’s Walker Lane belt is the setting for Lahontan Gold’s acquisition of Emergent Metals.

By Charles Pitts
Lahontan Gold Corp. is acquiring Emergent Metals Corp. in an all-share transaction that will give it full ownership of the West Santa Fe gold-silver project, eliminate royalties on West Santa Fe and the York claims, and add the adjacent New York Canyon property to its Nevada portfolio.
The transaction is primarily a consolidation of land, project rights and future economics in Nevada’s Walker Lane belt. Lahontan said the deal will create a regional claim package covering more than 93 square kilometres and simplify ownership around its Santa Fe Mine project.
Emergent shareholders will receive one Lahontan share for every 3.21 Emergent shares held, representing implied consideration of C$0.115 per Emergent share. Existing Lahontan shareholders are expected to own approximately 95.3% of the enlarged company, with Emergent shareholders holding the remaining 4.7%.
The arrangement agreement was announced on Sept. 16 and remains subject to shareholder, court, regulatory and other customary approvals.

Transaction snapshot
| Item | Terms or expected impact |
|---|---|
| Transaction structure | All-share plan of arrangement |
| Implied consideration | C$0.115 per Emergent share |
| Exchange ratio | 1 Lahontan share for every 3.21 Emergent shares |
| Existing Lahontan shareholder ownership | Approximately 95.3% |
| Emergent shareholder ownership | Approximately 4.7% |
| West Santa Fe ownership after closing | 100% |
| Future West Santa Fe payments eliminated | About C$2.39 million, or US$1.73 million |
| Royalties eliminated | 1% NSR on West Santa Fe and 1% NSR on 27 York claims |
| Combined Nevada land package | More than 93 square kilometres |
The transaction follows Lahontan’s earlier acquisition of the York claims, which are adjacent to the Santa Fe Mine. Two million Lahontan shares previously issued to Emergent in connection with that purchase will be returned to Lahontan’s treasury, according to the company. Lahontan valued those shares at approximately C$770,000 based on its 30-day volume-weighted average price.
Royalty elimination changes project economics
The most immediate financial rationale is the removal of the 1% net smelter return royalty attached to West Santa Fe and the 1% NSR royalty covering the 27 York claims at Santa Fe.
An NSR royalty is generally paid as a percentage of gross metal revenue, subject to the specific terms of the royalty agreement. Unlike operating costs, which may change with mine design, energy prices or production rates, a royalty can remain payable across the life of a project once revenue is generated.
Removing the royalties therefore gives Lahontan greater control over future revenue from the two areas. It also avoids the need to negotiate a separate royalty buyback and removes approximately C$2.39 million in future payments that would otherwise have been required to acquire the remaining interest in West Santa Fe.
The precise impact on project economics will depend on factors that have not yet been established, including mineable resources, production rates, recovery, capital costs, operating costs, permitting and metal prices. However, the ownership change improves the economic structure before those variables are incorporated into future technical studies.
The change is particularly relevant because Lahontan is advancing Santa Fe toward a potential restart and is continuing exploration at West Santa Fe. The company has said it plans to complete an updated preliminary economic assessment for Santa Fe and target a maiden resource estimate for West Santa Fe.

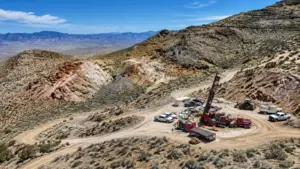
An exploration drill rig operates on an oxide gold target in Nevada.
New York Canyon extends the land package
Emergent’s New York Canyon project is another central component of the transaction. The project consists of two blocks of unpatented mining claims south of the Santa Fe Mine.
The northern block directly adjoins Santa Fe, simplifying the claim pattern and giving Lahontan greater control over ground between its existing project areas. That could allow exploration and mine-planning decisions to be considered across a more continuous land position rather than through separately owned claims.
The southern block has a different exploration profile. Lahontan describes it as prospective for a copper-gold-silver-molybdenum skarn and porphyry system. That gives the combined company exposure to a broader mineral system while keeping the main strategic focus on gold and silver.
The addition is consistent with the consolidation pattern seen across Nevada’s mining districts, where fragmented claim ownership can complicate drilling access, infrastructure planning, permitting and resource definition. A larger contiguous package does not guarantee a mine, but it can reduce the risk that a potentially economic zone is divided among multiple owners.

Heap-leach infrastructure and exploration ground in Nevada’s arid mining landscape.
The Santa Fe connection
Lahontan’s flagship Santa Fe Mine project covers 28.3 square kilometres and has a history of open-pit mining and heap-leach processing. The company has reported historic production of 359,202 ounces of gold and 702,067 ounces of silver from operations between 1988 and 1995.
In an Aug. 17 announcement, Lahontan reported a Santa Fe resource of 1.195 million ounces of gold equivalent in the indicated category and 1.19 million ounces of gold equivalent inferred. Those figures are based on a technical report and should not be treated as a reserve or production forecast.
The company is targeting mine development, permitting and additional drilling. The removal of the York royalty is relevant to that work because York is part of the resource and project area Lahontan is seeking to advance.
The acquisition also adds non-core assets, including a US$3.5 million promissory note from Fairchild Gold Corp., 12.5 million Fairchild shares and a 0.5% NSR royalty on the Golden Arrow property. Lahontan will also acquire properties and royalty interests in Quebec and leased mining claims in Nevada.
Those assets may provide future monetization options, but their value is separate from the core Nevada consolidation thesis. The central strategic benefit remains full control of West Santa Fe, royalty removal and a larger land package around Santa Fe.
What investors will watch next
The transaction still requires approval from Emergent shareholders, including a two-thirds majority of votes cast at the meeting, as well as court approval, TSX Venture Exchange acceptance and other regulatory consents.
Once completed, the main tests will shift from transaction mechanics to execution. Investors and project partners will likely focus on four areas:
- West Santa Fe resource definition: Lahontan must convert exploration results into a resource and then establish whether the mineralization supports a viable development concept.
- Santa Fe permitting and studies: An updated preliminary economic assessment and permitting progress will provide the next major tests of the restart strategy.
- Capital requirements: Consolidated ownership improves control, but construction, drilling and processing investments will still require capital.
- Commodity and operating assumptions: Gold and silver prices, recovery rates, labor, energy and construction costs will determine how much value the royalty savings ultimately create.
Lahontan CEO and President Kimberly Ann said the transaction advances the company’s objective of building a larger Nevada precious-metals company while maintaining disciplined capital allocation.
That strategy now depends on whether a broader and less encumbered land position can translate into a better-defined development plan. The deal removes several ownership barriers, but it does not remove the geological, permitting or financing risks that determine whether Nevada exploration assets become producing mines.
Investor take
This is the kind of mining M&A deal where the headline asset count matters less than the cleanup underneath it. Lahontan is using shares to secure full control of a project it already knows, remove 1% royalties, recover previously issued shares and add adjacent exploration ground.
The transaction is not a production guarantee, and investors will still need to see an updated economic study, a West Santa Fe resource and a credible capital plan. But the structure gives Lahontan a cleaner platform: fewer third-party claims on future revenue and more room to plan Santa Fe, West Santa Fe and New York Canyon as a connected Nevada district.
Social snippet
LinkedIn/X: Lahontan Gold’s acquisition of Emergent Metals is a Nevada consolidation play: 100% ownership of West Santa Fe, elimination of 1% NSR royalties on West Santa Fe and York, and a 93+ sq. km Walker Lane land package that adds New York Canyon. The next test is whether cleaner ownership can translate into stronger project economics.