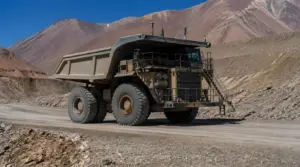
Copper production at a large open-pit mine remains constrained by operational disruptions, declining grades and long project timelines.

By Penny Langford
Copper prices remain near record territory even as futures markets consolidate. Spot copper was around $14,969 per tonne in late-September trading, while LME copper fell 0.87% and SHFE copper declined 0.26% in one session, according to market data reported by Reuters.
The retreat has not yet translated into relief for physical buyers in China. SHFE copper premiums have risen as fabricators and traders stock up before the country’s Golden Week holiday, tightening nearby availability and exposing a wider problem: copper supply is struggling to keep pace with demand from power grids, data centres, electric transport and industrial infrastructure.
The headline 600,000-tonne gap refers primarily to copper mine supply removed from expected 2026 output after disruptions at major operations. It is not the same as a confirmed 600,000-tonne refined-market deficit. The distinction matters because estimates for the refined balance remain divided, with some analysts forecasting a substantial shortfall and others expecting a surplus as high prices encourage scrap supply, substitution and demand restraint.
Copper market snapshot
The immediate market signals point to tight physical supply, but also to rising sensitivity to price.

| Indicator | Late-September reading | What it signals | Source |
|---|---|---|---|
| Spot copper | About $14,969/t | Near-record pricing and elevated replacement costs | Reuters market data |
| LME copper, one session | -0.87% | Short-term profit-taking and macro volatility | Reuters market data |
| SHFE copper, one session | -0.26% | Futures consolidation despite firm physical demand | Reuters market data |
| Shanghai spot premium | 660–810 yuan/t, average 735 yuan/t in the latest detailed SMM update | Tight nearby cathode availability | SMM |
| Estimated 2026 mine supply removed | About 600,000 tonnes | Disruptions at Grasberg and Kamoa-Kakula | Sprott analysis reported by The Northern Miner |
| 2026 annual TC benchmark | $0/t | Severe competition among smelters for concentrate | International Energy Agency |
SMM reported that Shanghai cathode premiums were already firm before the latest escalation, while inventories in major Chinese regions had fallen to unusually low levels. Pre-holiday restocking is adding to that pressure. Buyers are securing material ahead of Golden Week, while sellers are reluctant to release scarce units into a market where imported supply remains constrained.
The result is a market with two different signals: futures can ease modestly, but nearby physical copper can remain expensive.
The 600,000-tonne supply problem
Global mine production fell 1.1% year over year in the first half of 2026, according to Sprott Asset Management. The firm estimated that disruptions at Freeport-McMoRan’s Grasberg operation in Indonesia and Ivanhoe Mines’ Kamoa-Kakula complex in the Democratic Republic of Congo removed approximately 600,000 tonnes from expected full-year output.
That amount represents roughly 2.5% of annual global mine supply. It is large enough to change concentrate availability for smelters, particularly when inventories are geographically uneven.
Chile has added to the pressure. Sprott said Chilean mine output fell 6.6% in the first half, while July production was down 9.4% from a year earlier. Cochilco cut its 2026 Chilean production forecast to 5.27 million tonnes, citing weak output from Codelco, Escondida and Spence.
The supply response is also limited by geology and development timelines. Sprott’s Jacob White said copper projects take an average of about 17.5 years to move from discovery to production. Higher prices can improve project economics, but they cannot quickly replace lost tonnes from an operating mine or accelerate permitting, construction and commissioning.
That is why the current rally is not simply a response to stronger consumption. It is also a repricing of how difficult it has become to add reliable supply.

Mine disruptions and declining grades are limiting the industry’s short-term supply response.
Smelter treatment charges show the pressure downstream
The sharpest signal of concentrate tightness is visible in treatment and refining charges, or TC/RCs.
The IEA reported that the 2026 annual treatment charge benchmark settled at $0 per tonne, the lowest level reached in annual negotiations. Spot TC/RCs have remained negative since 2024 and fell to record lows as smelter capacity, particularly in China, expanded faster than mine concentrate production.
China has accounted for more than 90% of global copper smelter growth since 2005, according to the IEA. Its share of global smelter output reached about half in 2025.
This creates a structural mismatch. There may be substantial refining capacity, but not enough concentrate to operate all of it at attractive margins. Custom smelters must compete for feedstock, while integrated producers are better protected because they can draw on captive mine supply.
Low TC/RCs do not automatically guarantee higher copper prices. They show that the midstream is under financial pressure. If the condition persists, smelter production cuts, capacity rationalisation and greater reliance on recycled material could become necessary to rebalance the market.
Grid and data-centre demand provide a durable floor
Copper demand is broad-based, but electricity infrastructure is becoming increasingly important.
The IEA identifies grids, electric vehicles, construction, industry and data centres as major sources of future consumption. Data centres require copper for power distribution, cooling systems, transformers, switchgear and cabling. Grid upgrades require large volumes of copper-intensive conductors and related equipment.
Sprott similarly identified power grids, artificial-intelligence data centres and defence infrastructure as areas of rising demand. These uses are less discretionary than some construction or consumer applications, although project timing can still shift when financing costs rise or equipment becomes expensive.
The demand picture is therefore supportive but not unlimited. At nearly $15,000 per tonne, copper becomes a significant cost input for wire manufacturers, cable producers, utilities and equipment suppliers. Some projects may be delayed, redesigned or partially substituted with aluminium where engineering requirements allow.

Data centres use copper across power distribution, cooling and high-capacity electrical systems.
Copper price forecast 2026: base, bull and bear cases
The following framework uses LME copper prices in dollars per tonne. The ranges are scenario bands rather than investment recommendations or precise point forecasts.
| Year | Scenario | Price range | Physical-market assumption | Main drivers |
|---|---|---|---|---|
| 2026 | Bull | $14,500–$16,500/t | Deficit of roughly 330,000–600,000 tonnes, with very low inventories and tight concentrate | Mine disruptions persist; Golden Week buying extends; TC/RCs remain depressed; grid and data-centre demand stays strong |
| 2026 | Base | $12,000–$14,500/t | Near balance to moderate deficit; scrap and demand response offset part of lost mine supply | Supply remains constrained, but high prices curb consumption and improve recycling |
| 2026 | Bear | $10,000–$11,500/t | Surplus develops as disruptions ease and scrap flows increase | Global slowdown, weaker Chinese demand, substitution and a recovery in visible inventories |
| 2027 | Bull | $14,000–$16,000/t | Structural deficit widens as new supply fails to match demand | Delayed projects, low grades, continued grid investment and accelerating AI infrastructure |
| 2027 | Base | $12,500–$14,000/t | Small deficit or mixed balance | Demand remains firm, but new capacity and recycling prevent a severe squeeze |
| 2027 | Bear | $10,000–$11,500/t | Large surplus from new projects, scrap and weaker consumption | Macro recession, stronger smelter availability and slower electrification spending |
The base case is deliberately wider than a traditional annual-average forecast because the market is experiencing regional dislocations. Copper can trade at a high global benchmark while physical premiums in China rise sharply or U.S. inventories build because metal is moving toward specific markets.
J.P. Morgan’s published outlook illustrates the downside risk. Its research has pointed to a medium-term support area around $11,100–$11,200/t if geopolitical and macroeconomic pressures weaken industrial demand. Goldman Sachs, meanwhile, has argued that high prices could eventually encourage a surplus by lifting scrap supply and reducing consumption growth.
The bull case requires more than a single mine disruption. It requires disruptions to persist while inventories remain low, smelter fees stay depressed and demand from grids and data centres continues to expand. A sustained 600,000-tonne loss of expected mine supply would make that outcome more plausible, but it would still depend on how much metal is released from scrap, bonded warehouses and strategic inventories.
The main risk is demand destruction
The copper market’s strongest support can also become its biggest risk.
SMM reported that Chinese downstream buyers remained selective because high premiums reduced willingness to purchase beyond immediate needs. That is an early sign of demand destruction: end users continue operating, but they reduce inventory, delay purchases or switch to lower-cost alternatives.
J.P. Morgan has also warned that higher energy prices could weaken global growth and reduce copper demand. Its research estimated that a 10% increase in oil prices could reduce global GDP by approximately 0.16%, while copper demand has an estimated 1.2 beta to global GDP. Under one scenario involving oil around $110 per barrel, the bank said its 2026 copper-demand growth estimate could be reduced by 1.4 percentage points.
That sensitivity makes the bear case credible even in a structurally tight market. Copper does not need to become abundant for prices to fall; demand only needs to slow faster than supply.
Outlook: tight market, volatile path
The late-September market is sending a clear but incomplete message. Near-record prices, firm SHFE premiums and depressed treatment charges all point to physical tightness. Mine disruptions and declining Chilean output reinforce the supply case, while grids and data centres provide durable demand support.
But the refined balance remains contested. Some forecasts point to a deficit of several hundred thousand tonnes, while Goldman Sachs, Macquarie and Cochilco have published surplus-based scenarios. The most useful interpretation is not that a 600,000-tonne refined deficit is guaranteed, but that the industry has lost approximately 600,000 tonnes of expected mine supply at a time when new projects cannot respond quickly.
For the copper price forecast 2026, the central risk is a market that remains fundamentally tight but becomes increasingly price-sensitive. If inventories continue falling and supply disruptions persist, copper could hold the mid-teens range. If demand destruction, recycling and macroeconomic weakness gain momentum, a retreat toward $10,000–$11,500 per tonne remains possible.
The defining question is therefore not whether copper is scarce. It is whether new supply can arrive before high prices begin to destroy enough demand to restore balance.